Skip to content
Sabse Sasta Loan Offer — CIBIL pe Zero Impact
GoCredit
GoCredit AI
★★★★★4.8·40L+ users
INSTALL

Finance News — Page 6

News Padhne Se Loan Nahi Milta

GoCredit ka AI tumhari taraf se apply karta hai — CIBIL pe zero impact. Real approved offers minutes mein.

Get Real Offers — Free →
100 articles
EPS Pension Stopped? 1 Missing Doc Cuts Your Pay
📋 Financial Planning
38d ago
💰
85 lakh pensioners

Your EPS pension stops if you skip this one annual step

EPS Pension Stopped? 1 Missing Doc Cuts Your Pay

🤯 Missing this form costs pensioners more than 12 months of chai money — it freezes...

Read Full Story
📋 TL;DR

If you receive a monthly pension under EPS-95, you must submit a Life Certificate once a year. Skip it and EPFO pauses your pension payments completely until you comply. Here's exactly what to do.

📰 What Happened

EPFO mandates that all EPS-95 pension recipients submit an annual Life Certificate (Jeevan Pramaan Patra) to confirm they are alive and eligible to receive pension payments.

Failure to submit this certificate by the due date — typically in November each year — results in EPFO suspending monthly pension disbursements until the document is received.

Over 85 lakh active EPS-95 pensioners across India are subject to this rule, making timely submission critical to uninterrupted retirement income.

🎯 What You Should Do

Download the Jeevan Pramaan app on your Android phone and submit your Life Certificate digitally using Aadhaar-linked biometric authentication — takes under 10 minutes.

💡

If your pension was recently paused, visit your nearest EPFO office or authorised bank branch with your PPO number and Aadhaar card to reactivate it and claim pending arrears.

Mark November 1 as an annual reminder in your phone calendar so you never miss the Life Certificate submission window for EPS-95 pension continuity.

💡 Pro Tip

Pensioners above 80 years can get a doorstep Life Certificate submission through the India Post Payments Bank (IPPB) postman service — free of charge, no travel needed.

AI finds your cheapest loan from 100+ lenders

Check Your PF Status
Ayushman Bharat: Is Your Family Eligible for ₹5L Cover?
🛡️ Insurance
38d ago
💰
₹5 lakh/year

Your family gets this much free health cover under Ayushman Bharat

Ayushman Bharat: Is Your Family Eligible for ₹5L Cover?

🤯 ₹5 lakh health cover costs ₹25,000–₹40,000/year privately — Ayushman gives it free,...

Read Full Story
📋 TL;DR

West Bengal has joined the Ayushman Bharat scheme, giving 1.5 crore low-income families up to ₹5 lakh per year in free hospitalisation cover. If you qualify, you can get cashless treatment at thousands of empanelled hospitals across India — at zero premium.

📰 What Happened

West Bengal has officially launched Ayushman Bharat PM-JAY, bringing an estimated 1.5 crore families in the state under the scheme's ₹5 lakh annual health cover.

Empanelled hospitals — both government and private — across West Bengal and the rest of India are now available for cashless treatment to eligible beneficiaries in the state.

Eligibility is determined by the SECC 2011 database; qualifying families receive a free Ayushman card linked to Aadhaar with no premium or co-payment required.

🎯 What You Should Do

Check your eligibility in 2 minutes: visit beneficiary.nha.gov.in or the Ayushman Bharat app, enter your mobile number or Aadhaar, and see if your family is listed as a beneficiary.

💡

Download or generate your Ayushman card from the NHA portal — you'll need Aadhaar-based eKYC to activate it, so keep your Aadhaar-linked mobile number handy.

Locate empanelled hospitals near you before any emergency — search at hospitals.pmjay.gov.in by district so you know which private hospitals accept Ayushman cards cashlessly.

💡 Pro Tip

Pro tip: Even if you have private health insurance, use your Ayushman card first for eligible treatments — it preserves your private policy's No Claim Bonus and keeps your sum insured intact for bigger emergencies.

Insurance + loans sorted — one app for your money

Get GoCredit
Home Healthcare: Does Your Health Plan Cover It?
🛡️ Insurance
38d ago
💰
₹0 reimbursed

What most health policies pay for hospital-at-home care you actually need

Home Healthcare: Does Your Health Plan Cover It?

🤯 A 3-day hospital stay can cost ₹40,000+; the same care at home often costs half — yet...

Read Full Story
📋 TL;DR

Home-based medical care is booming in India, but most health insurance policies still don't cover it. Here's what 'home healthcare' means, why it matters, and how to check if your policy actually protects you when you're treated at home instead of a hospital.

📰 What Happened

Home-based medical care — where doctors, nurses, and equipment come to your house instead of hospitalising you — is growing rapidly across 300+ Indian cities.

Insurance companies are beginning to offer structured 'home healthcare' add-ons or riders, but standard base policies often still cap or exclude domiciliary treatment cover.

Rising hospital costs and bed shortages post-COVID have made at-home care attractive, yet most policyholders don't realise their existing plan may not reimburse these expenses.

🎯 What You Should Do

Search your health policy document for the word 'domiciliary' — if absent, call your insurer today and ask specifically whether home-based medical treatment is covered.

💡

Compare top-up or super top-up plans that explicitly include domiciliary hospitalisation cover, especially if you have elderly parents or manage a chronic condition at home.

If buying a new policy, ask the insurer for the full list of conditions excluded from home healthcare cover before signing — this list can include diabetes and hypertension.

💡 Pro Tip

Some IRDAI-approved policies now cover dedicated 'home healthcare' as a separate defined benefit — different from domiciliary hospitalisation. Ask for both by name when renewing.

Insurance + loans sorted — one app for your money

Get GoCredit
Idle Savings Account? You're Losing ₹12,000 a Year
📋 Financial Planning
38d ago
📉
3–4% savings rate vs 12% inflation-adjusted loss

Your idle savings account is silently eroding your real wealth every month

Idle Savings Account? You're Losing ₹12,000 a Year

🤯 ₹5 lakh sitting idle in savings earns less per month than a family's grocery bill —...

Read Full Story
📋 TL;DR

Keeping large sums in a regular savings account feels safe, but with inflation at 5–6%, your money loses real value fast. Here's how to put idle cash to work without stress.

📰 What Happened

Most Indian savings accounts pay 2.7%–4% annual interest, well below India's average CPI inflation of 5–6%, meaning idle cash loses real purchasing power every month.

Salaried professionals often accumulate several lakhs in savings accounts as bonuses, increments, and freelance income pile up — postponing investment decisions costs them compounded returns over years.

Simple, low-risk alternatives like sweep-in FDs, liquid mutual funds, and short-duration debt funds offer 6%–7.5% returns with near-instant liquidity — yet most account holders never activate them.

🎯 What You Should Do

Call or log in to your bank app today and activate the sweep-in FD feature — it auto-moves balances above your chosen limit into FDs earning 6%–7% while keeping your money accessible.

💡

Calculate your 3–6 month emergency fund requirement and move any surplus above that amount into a liquid mutual fund or money market fund for better returns with T+1 withdrawal.

Set up an automatic SIP on your salary credit date so money moves to investments before you spend it — even ₹5,000–₹10,000 a month compounded over 10 years builds significant wealth.

💡 Pro Tip

Arbitrage mutual funds currently yield ~6.5–7% and are taxed as equity (10% LTCG after 1 year) — a smarter parking spot than FDs for anyone in the 30% tax bracket.

AI finds your cheapest loan from 100+ lenders

Explore Better Savings Options
Foreign Assets Scheme 2026
💰 Tax & Budget
38d ago
💰
₹0 penalty

Disclose your foreign assets now and avoid massive tax penalties later

Foreign Assets Scheme 2026 — Aug 2026

🤯 The penalty for hiding foreign assets can be ₹10 lakh flat — that's 4 years of chai...

Read Full Story
📋 TL;DR

The Indian government has launched a one-time scheme letting eligible taxpayers declare undisclosed foreign assets and income with reduced penalties. If you have overseas accounts, property, or investments you haven't declared, this window could save you from massive fines.

📰 What Happened

India's government launched the Foreign Assets of Small Taxpayers Disclosure Scheme (FAST) 2026, a one-time opportunity for eligible residents to declare previously undisclosed foreign assets and income.

The scheme targets smaller taxpayers — salaried individuals, small business owners, and those with inherited foreign holdings — who may have overlooked declaration obligations, not large-scale evaders.

India receives automatic financial account data from over 100 countries under FATCA and CRS agreements, meaning undisclosed foreign accounts are increasingly detectable by the Income Tax Department.

🎯 What You Should Do

Check your ITR's Schedule FA (Foreign Assets) from the last 3 years — if you hold any overseas bank account, property, or investment not listed there, you may need to disclose it under this scheme.

💡

Consult a tax professional familiar with the Black Money (Undisclosed Foreign Income and Assets) Act before filing — declarations under this scheme require accurate valuation of assets in INR.

File your disclosure before the scheme's deadline; once closed, the IT Department can levy a flat ₹10 lakh penalty per undisclosed asset plus 30% tax on the asset value under the Black Money Act.

💡 Pro Tip

Even a dormant NRI bank account you forgot to close counts as a foreign asset requiring declaration in Schedule FA of your ITR — non-disclosure is a violation even if the balance is zero.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
📊

Free CIBIL Score Check

Check your credit score instantly — zero impact on CIBIL

Check Score Free
2 Houses? Use HUF to Save 54F Capital Gains Tax
💰 Tax & Budget
38d ago
💰
₹0 tax on capital gains

Section 54F can wipe your entire share sale tax if you plan right

2 Houses? Use HUF to Save 54F Capital Gains Tax

🤯 The tax you save on a ₹50L share sale could fund 13 years of your Netflix subscription.

Read Full Story
📋 TL;DR

If you own two houses, you normally can't claim Section 54F tax exemption when selling shares. But gifting one property to your HUF may legally revive your eligibility — here's how it works and what to watch out for.

📰 What Happened

Section 54F exemption on long-term capital gains from share sales is blocked if you own more than one residential property on the sale date.

Transferring one property to a Hindu Undivided Family (HUF) — a separate legal tax entity — may reduce your personal property count and revive 54F eligibility.

Income tax rules treat HUFs as distinct taxpayers with their own PAN and ITR, making inter-family property transfers a legitimate but scrutiny-prone tax planning tool.

🎯 What You Should Do

Check how many residential properties are in your personal name before you sell any shares — count matters on the exact date of sale.

💡

Consult a CA specialising in HUF taxation to assess whether forming or using an existing HUF for property transfer is valid in your specific case.

Ensure your HUF is properly constituted with a PAN card, bank account, and deed before attempting any property transfer — a poorly documented HUF invites IT scrutiny.

💡 Pro Tip

The HUF must be genuinely operational — with its own PAN, bank account, and documented corpus — before any property transfer. A last-minute HUF formed purely to claim 54F will almost certainly be challenged during tax assessment.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
IT Refund Scam: 5 Signs Your Email Is Fake
💰 Tax & Budget⚠️BORROWER ALERT
38d ago
💰
₹0 refund received — after scammers stole it first

Fake IT Department emails are redirecting your tax refund to fraudsters

IT Refund Scam: 5 Signs Your Email Is Fake

🤯 One phishing click can hand scammers your entire ₹15,000 TDS refund — gone faster than...

Read Full Story
📋 TL;DR

Fraudsters are sending fake Income Tax Department emails and creating lookalike websites to steal your PAN, bank details, and tax refunds. Here is how to spot a scam and what to do if you get targeted.

📰 What Happened

Fraudsters are impersonating the Income Tax Department via fake emails and cloned websites to harvest PAN numbers, bank account details, and OTPs from taxpayers.

These scam messages typically promise pending refunds, warn of account suspension, or claim a tax notice has been issued — all designed to trigger panic and immediate action.

The real Income Tax Department only uses the official portal incometax.gov.in for refunds and notices; it never asks for passwords, OTPs, or full bank account numbers over email.

🎯 What You Should Do

Check your actual refund status by logging directly into incometax.gov.in — never through a link in any email, SMS, or WhatsApp message.

💡

Report suspicious emails or fake websites immediately at cybercrime.gov.in (National Cyber Crime Reporting Portal) and forward the email to incident@cert-in.org.in.

Call your bank's 24-hour fraud helpline within 30 minutes of sharing any sensitive details on a suspicious site — early reporting can trigger a zero-liability freeze on your account.

💡 Pro Tip

Pro tip: The IT Department's official helpline is 1800-103-0025. If you receive a suspicious notice, call this number to verify whether it is genuine before taking any action.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
Monsoon Car Damage: Is Your OD Cover Enough?
🛡️ Insurance
38d ago
💰
₹3.5 lakh+

Your monsoon car damage bill if you skip Own Damage cover this season

Monsoon Car Damage: Is Your OD Cover Enough?

🤯 Fixing a flooded car engine costs more than 3 years of full OD premium — roughly ₹3.5L...

Read Full Story
📋 TL;DR

Third-party car insurance is legally mandatory but won't pay a rupee for your own car's monsoon damage. Own Damage cover does — and with the right add-ons, it can save you lakhs when the rains hit hard.

📰 What Happened

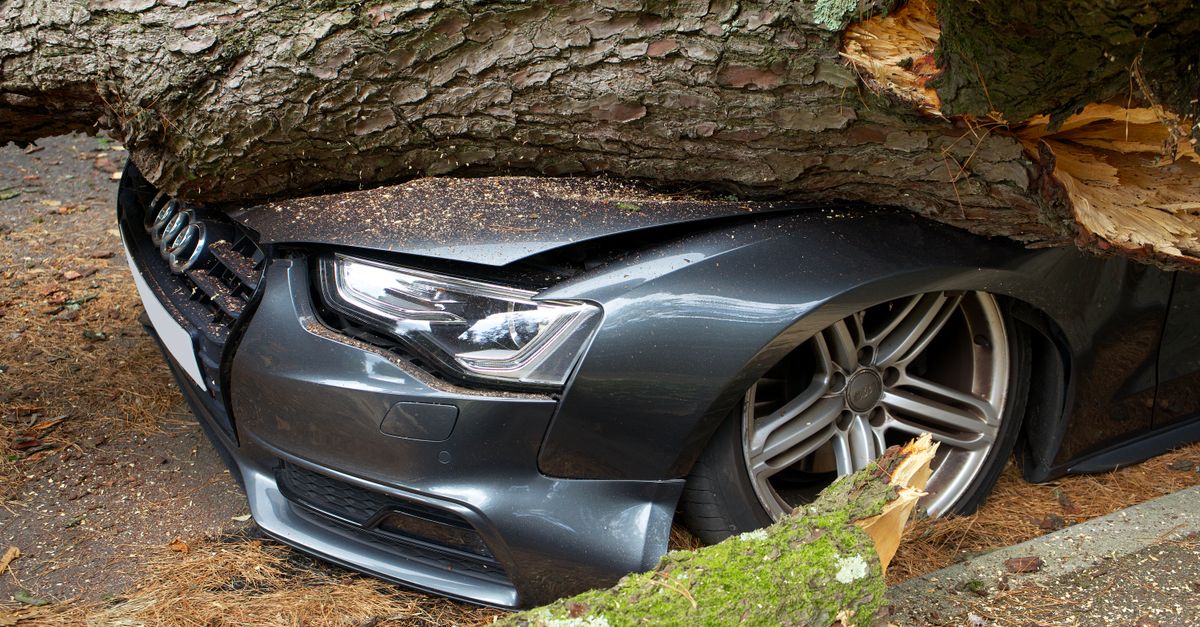
Monsoon season brings a spike in car damage claims — flooding, fallen trees, waterlogged engines, and hailstorms cause damage that third-party-only insurance does not cover at all.

Own Damage (OD) motor insurance covers repair or replacement costs for your vehicle from natural calamities, fire, theft, and accidents — it is optional under Indian law but critical financially.

Several add-ons like engine protection, zero depreciation, and roadside assistance fill gaps that even a standard OD policy leaves open, especially for monsoon-specific risks.

🎯 What You Should Do

Check your policy document right now — look for 'Own Damage' or 'Package Policy' on the cover page; if it says 'Third Party Only', you have zero coverage for your car's monsoon damage.

💡

Add engine protection cover before the monsoon peaks — this single add-on covers hydrostatic lock (flooded engine), which standard OD policies explicitly exclude and can cost ₹1.5L–₹3.5L to fix.

Compare comprehensive car insurance renewal quotes on IRDAI-regulated aggregator platforms — bundling zero depreciation, engine protection, and roadside assistance typically adds only ₹2,000–₹5,000 to your annual premium.

💡 Pro Tip

Never attempt to start a waterlogged car — hydrostatic lock voids most engine protection claims. Call your insurer's helpline first and let them tow it to an authorised garage.

Insurance + loans sorted — one app for your money

Get GoCredit
Health Insurer Hides 44%? Check 3 Numbers Before You Buy
🛡️ Insurance
38d ago
📉
Only 56% claims paid

Some health insurers quietly reject nearly half your claims

Health Insurer Hides 44%? Check 3 Numbers Before You Buy

🤯 Indians spend ₹800/month on OTT but skip reading claim data that could save ₹5 lakh

Read Full Story
📋 TL;DR

Before buying health insurance, check your insurer's claim settlement ratio, complaint volume, and coverage limits. IRDAI publishes this data publicly every year — but most buyers never look at it, and end up with a policy that rejects claims when it matters most.

📰 What Happened

IRDAI requires every health insurer to publish annual public disclosures — including claim settlement ratios, complaint data, and product-level details — in a standardised format called Schedule NL-47.

Claim settlement ratios vary dramatically across insurers, with some paying out under 60% of health claims filed — a gap most policyholders discover only at the time of a medical emergency.

Most Indian buyers choose health insurance based on premium price or agent recommendation, without ever checking publicly available IRDAI data that shows how each insurer actually performs on claims.

🎯 What You Should Do

Visit IRDAI's official website (irdai.gov.in) and look up your shortlisted insurer's annual report — compare Claim Settlement Ratio, Incurred Claims Ratio, and complaints per 10,000 claims before buying.

💡

Check the insurer's cashless hospital network specifically in your city or district — use their online hospital locator filtered by your pin code, not the national headline number.

Avoid any IRDAI-registered health insurer with a Claim Settlement Ratio below 85% or more than 30 complaints per 10,000 claims, regardless of how low their annual premium looks.

💡 Pro Tip

Pro tip: An Incurred Claims Ratio (ICR) between 70–100% signals a financially healthy insurer — below 50% often means aggressive claim rejection, above 110% signals the insurer may be heading for trouble.

Insurance + loans sorted — one app for your money

Get GoCredit
Gold Loan Boom: Are You Paying 24% Interest Needlessly?
🏦 Bank Updates
38d ago
💰
₹705 crore

Gold loan profits soared 4x — are you overpaying on your pledge?

Gold Loan Boom: Are You Paying 24% Interest Needlessly?

🤯 The interest on a ₹1 lakh gold loan for 12 months can buy you 200 cups of chai — every...

Read Full Story
📋 TL;DR

Gold loans are exploding in India as NBFCs report massive profits. Before you pledge your family's jewellery, understand the real cost, hidden charges, and smarter alternatives so you don't lose your gold over a short-term cash crunch.

📰 What Happened

Major gold loan NBFCs in India are reporting sharp profit jumps, driven by rising net interest income as demand for gold-backed credit surges across urban and semi-urban households.

Gold prices have touched record highs in 2024-25, increasing the collateral value of jewellery and allowing borrowers to unlock larger loan amounts against the same weight of gold.

RBI regulates gold loans strictly — lenders cannot lend more than 75% of the gold's market value (LTV cap), and must follow fair auction procedures if a borrower defaults.

🎯 What You Should Do

Compare rates before pledging: check your bank's gold loan rate (typically 9-13%) against the NBFC rate — the gap can save you ₹15,000-₹25,000 on a ₹2 lakh loan over a year.

💡

Read the auction clause carefully — ask the lender exactly how many days of default trigger an auction notice, and get it in writing before signing any pledge agreement.

Calculate the all-in cost: add processing fee + valuation fee + interest + foreclosure charge to get the true annual cost — never compare just the headline interest rate.

💡 Pro Tip

Pro tip: if you only need cash for 30-60 days, an overdraft against gold (not a term gold loan) charges interest only on days used — can cut your actual cost by 60-70%.

Is your bank safe? Check lender ratings on GoCredit

Check Lenders
🎯

AI Loan Agent — 100+ Lenders

AI scans all lenders and finds your cheapest EMI automatically

Find Cheapest Loan
Ladli Behna ₹1,500 Delayed? Check Your Account Now
📋 Financial Planning
38d ago
💰
₹1,500/month

Your Ladli Behna benefit could hit your account any day this August

Ladli Behna ₹1,500 Delayed? Check Your Account Now

🤯 ₹1,500 covers roughly 50 cups of cutting chai — or a full month's mobile recharge plus...

Read Full Story
📋 TL;DR

Madhya Pradesh's Ladli Behna Yojana gives ₹1,500 every month to eligible women directly into their bank accounts. If your August installment hasn't arrived yet, here's what you should check and when to expect it.

📰 What Happened

Madhya Pradesh's Ladli Behna Yojana transfers ₹1,500 per month directly to eligible women's bank accounts under DBT, with August being the 39th installment cycle.

Payments are typically processed between the 1st and 10th of each month, but bank-level processing and Aadhaar-seeding verification can delay credit by several days.

Common reasons for missed installments include Aadhaar not linked to the receiving bank account, dormant accounts, or outdated bank details on the beneficiary's registration profile.

🎯 What You Should Do

Check your payment status right now at cmladlibahna.mp.gov.in using your registered mobile number — it shows real-time DBT credit history.

💡

Verify your Aadhaar is seeded to your active bank account by visiting your bank branch or checking via your bank's mobile app under 'Aadhaar linking status'.

If bank details have changed since registration, call CM Helpline 181 or visit your local anganwadi centre immediately to update your account number before the next cycle.

💡 Pro Tip

Pro tip: If your account is dormant (no transaction in over 12 months), DBT credits get rejected automatically — make one small transaction to reactivate it before the transfer date.

AI finds your cheapest loan from 100+ lenders

Check Your DBT Status
100% Equity Portfolio: Is Your Risk Worth the Return?
📊 Investing
38d ago
📉
100% equity = 2x gain, but 3x the gut-punch

Your all-equity portfolio grows more — but your nerves (and withdrawals) may not survive the ride

100% Equity Portfolio: Is Your Risk Worth the Return?

🤯 A 30% market crash on ₹10L savings hurts more than skipping chai for 8 years straight.

Read Full Story
📋 TL;DR

All-equity portfolios beat fixed income over 20 years, but once you adjust for volatility and drawdowns, a balanced 50:50 mix often delivers better risk-adjusted returns — especially for investors nearing retirement or needing regular income.

📰 What Happened

Over a 20-year horizon, a 100% equity portfolio (tracking broad Indian indices) has historically delivered the highest absolute CAGR, outpacing both pure debt and balanced portfolios.

When risk-adjusted return metrics like the Sharpe Ratio are applied, a 50:50 equity-debt mix frequently matches or beats pure equity — delivering strong gains with far lower peak-to-trough drawdowns.

Fixed-income-only portfolios (FDs, bonds, debt funds) consistently lag equity over 20-year periods in real (inflation-adjusted) terms, making them a poor standalone long-term wealth strategy.

🎯 What You Should Do

Check your current portfolio allocation right now — if you are within 5 years of a major financial goal, shift at least 30–40% into debt instruments like PPF, debt mutual funds, or short-term FDs.

💡

Calculate your personal 'sleep test' — if a 35% portfolio drop would make you sell everything, reduce equity below 70% and use a hybrid or balanced advantage fund instead.

Review your SIP funds' category: if all your SIPs are in pure equity (mid-cap, small-cap, sectoral), add one hybrid or aggressive hybrid fund to smooth out your overall portfolio volatility.

💡 Pro Tip

Pro tip: Balanced Advantage Funds (BAFs) automatically shift between equity and debt based on market valuations — giving you risk-adjusted returns without manual rebalancing every year.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
Dividend Yield Funds: Is Your SIP Underperforming?
📊 Investing
38d ago
📉
10%+

Only 2 dividend yield funds crossed this return in the past year

Dividend Yield Funds: Is Your SIP Underperforming?

🤯 The gap between the best and worst dividend yield fund last year was wider than a...

Read Full Story
📋 TL;DR

Dividend yield mutual funds had very mixed results in the last year. Only two funds beat 10% returns while several others lagged badly. Portfolio choices and fund expenses made a huge difference. Here is what you need to know before investing.

📰 What Happened

Only two dividend yield mutual funds delivered returns above 10% over the past one year, while most of the category trailed significantly.

Wide differences in equity allocation strategy and stock selection within each fund's portfolio drove the large performance gap across the category.

Higher expense ratios in some funds compounded the underperformance, silently reducing net returns for investors even before market volatility is considered.

🎯 What You Should Do

Check your dividend yield fund's 1-year and 3-year returns on AMFI's website and compare them against the category average — not just absolute numbers.

💡

Review the expense ratio of your fund; switch to a direct plan if you are currently in a regular plan, as it can save 0.5%–1% annually.

Avoid assuming dividend yield funds give you regular dividend income — returns are from capital appreciation, so ensure this aligns with your actual financial goal.

💡 Pro Tip

Pro tip: Within the same mutual fund category, top and bottom performers can differ by 5–8% annually — always compare peer funds before adding fresh SIP money.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
Defective ITR Notice? Your 15-Day Fix Explained
💰 Tax & Budget
38d ago
15 days

Your window to fix a defective ITR before it's treated as never filed

Defective ITR Notice? Your 15-Day Fix Explained

🤯 Missing one tax field can void your entire ₹1.5L 80C saving — like losing a month's...

Read Full Story
📋 TL;DR

Got a defective ITR notice for AY 2026-27? Under Section 139(9), you have 15 days to correct errors or your return is treated as invalid — meaning no refund, no loss carry-forward, and possible penalties.

📰 What Happened

Income Tax Department is issuing defective return notices under Section 139(9) for AY 2026-27 to taxpayers whose ITRs have missing schedules, wrong form selection, or income-TDS mismatches.

A defective notice gives you 15 days to log into the income tax portal and submit a corrected return — the officer can extend this deadline if you request it in writing with valid reasons.

If the notice is ignored entirely, your ITR is treated as invalid — equivalent to never having filed — triggering late-filing penalties and loss of refunds or carry-forward benefits.

🎯 What You Should Do

Log in to incometax.gov.in right now, go to 'Pending Actions' → 'Response to Outstanding Demand', and check if any defective notice has been issued for AY 2026-27.

💡

Compare your filed ITR with your Form 26AS, AIS, and TIS to spot the exact mismatch — fix the specific field flagged in the notice before resubmitting your corrected return.

If you need more than 15 days, write formally to your assessing officer requesting an extension before the deadline passes — do not simply wait and hope the notice goes away.

💡 Pro Tip

Pro tip: Even if you correct and resubmit in response to a 139(9) notice, verify the portal shows status 'Return Filed — Defect Rectified', not 'Defective' — a stuck status means your fix didn't register.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
Retire at 45? You Need ₹12 Crore — Here's Why
📋 Financial Planning
39d ago
💰
₹12-15 crore

Your early retirement corpus could be this large — and most people underestimate it

Retire at 45? You Need ₹12 Crore — Here's Why

🤯 ₹12 crore sounds wild, but at ₹60K/month spend, inflation eats your corpus before you...

Read Full Story
📋 TL;DR

Early retirement sounds amazing — quit at 40 or 45, travel, pursue passion. But a 50-year retirement horizon, rising healthcare costs, and inflation make this far harder than most Indian professionals realise. Here's what the real math looks like.

📰 What Happened

Early retirement — quitting work at 40-45 — has become a genuine financial goal for thousands of Indian salaried professionals and startup employees, fuelled by FIRE (Financial Independence, Retire Early) content online.

The core challenge is that retiring at 40 means funding 45-50 years of expenses, a timeframe that exposes your corpus to multiple inflation cycles, healthcare cost surges, and prolonged market downturns.

Most early retirement calculators used in India underestimate real inflation (especially for healthcare and education for young children), leading people to believe they need far less than they actually do.

🎯 What You Should Do

Calculate your 'real' monthly expense by adding current spending, expected healthcare premium at age 60, and one foreign trip or major lifestyle expense per year — use this, not a rounded-down figure, as your base.

💡

Stress-test your retirement corpus using a 6% inflation assumption and a 30% portfolio drawdown in year 1 of retirement — free tools like FIRECalc (adapted for Indian returns) or freefincal's robo-advisory can help.

Buy a comprehensive health insurance policy NOW while you are young and healthy — a ₹1 crore super top-up plan costs under ₹15,000 per year in your 30s but will be unaffordable or unavailable once you have pre-existing conditions.

💡 Pro Tip

Pro tip: the safest early retirement strategy in India uses a 'bucket system' — 2 years of expenses in liquid FDs, 5 years in debt funds, and the rest in equity — so a market crash never forces you to sell equities at a loss.

AI finds your cheapest loan from 100+ lenders

Plan Your Retirement Now
🛡️

Recovery Harassment? Get Help

Loan Kavach: legal team fights harassment calls for you

Get Protection
Bank Holiday Aug 15: Are Your Transactions Safe?
🏦 Bank Updates
39d ago
🚨
26 bank holidays in 2025

Your branch could be shut more days than you expect this year

Bank Holiday Aug 15: Are Your Transactions Safe?

🤯 Missing a bank holiday can cost you a bounced EMI fee of ₹500–₹1,000 — more than a...

Read Full Story
📋 TL;DR

Banks are closed on August 15 for Independence Day. But your money isn't stuck — UPI, ATMs, and net banking work. Here's what actually stops and what you can plan around.

📰 What Happened

August 15 is a national public holiday — all bank branches across India remain closed for Independence Day.

Digital channels including UPI, IMPS, and net banking continue to operate normally since they run on 24x7 infrastructure.

RTGS settlements for high-value transfers above ₹2 lakh may be delayed; cheque clearances resume on the next working day.

🎯 What You Should Do

Fund your EMI or loan repayment account at least one day before August 15 to avoid a bounce charge and a CIBIL score drop.

💡

Use UPI or IMPS for any urgent money transfers on the holiday — avoid scheduling RTGS transfers that require same-day settlement.

Check the RBI's 2025 bank holiday list for your specific state, as regional festivals can add extra branch closure days beyond national holidays.

💡 Pro Tip

Pro tip: A cheque presented on a bank holiday is not dishonoured — it simply clears on the next working day, giving you a small but real buffer if your account is tight.

Is your bank safe? Check lender ratings on GoCredit

Check Lenders
23,467 Tax Appeals Dropped: Is Your Case Closed?
💰 Tax & Budget
39d ago
🎯
23,467 tax appeals dropped

Your pending income tax dispute may now be automatically closed

23,467 Tax Appeals Dropped: Is Your Case Closed?

🤯 23,467 cases dropped — that's more appeals than a busy Mumbai tax officer sees in 30...

Read Full Story
📋 TL;DR

The Income Tax Department has dropped over 23,000 departmental appeals after raising the minimum tax amount needed to fight a case in court. If your dispute involves smaller amounts, the government may no longer be pursuing it — meaning relief could be on its way.

📰 What Happened

India's Income Tax Department withdrew 5,978 filed appeals and chose not to file 17,489 new ones after the government raised minimum monetary thresholds for departmental appeals.

The new limits are ₹60 lakh for ITAT, ₹2 crore for High Courts, and ₹5 crore for the Supreme Court — cases below these amounts will no longer be pursued by the department.

The move is part of a broader effort to reduce litigation backlog; lakhs of tax disputes have been pending for years across tribunals and courts in India.

🎯 What You Should Do

Check your pending tax dispute paperwork and identify the exact 'tax effect' (disputed amount) — if it falls below ₹60 lakh at ITAT level, the department may have already dropped its appeal.

💡

Contact your chartered accountant or tax consultant to verify whether a formal closure or stay-vacation order needs to be obtained from the relevant tribunal or court.

If you had paid demand amounts under protest while an appeal was pending, ask your CA to file for a refund with interest under Section 244A once the case is formally closed.

💡 Pro Tip

Even if the department drops its appeal, the tribunal must pass a formal order in your favour — don't assume the case is closed until you have that written order in hand.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
Section 80GGC Deduction: Can You Claim It?
💰 Tax & Budget
39d ago
💰
₹2.31 lakh

This penalty was deleted — know your rights before paying yours

Section 80GGC Deduction: Can You Claim It?

🤯 A ₹3.71 lakh political donation deduction costs less tax than 3 months of a mid-range...

Read Full Story
📋 TL;DR

A taxpayer's ₹2.31 lakh income-tax penalty for claiming a political donation deduction under Section 80GGC was cancelled by a tax tribunal. The department couldn't prove the claim was wrong. Here's what this means for anyone claiming deductions on their ITR.

📰 What Happened

An income-tax tribunal in Ahmedabad cancelled a ₹2.31 lakh penalty on a taxpayer who had claimed a ₹3.71 lakh deduction for a political donation under Section 80GGC.

The tribunal ruled the tax department failed to prove the deduction amounted to under-reporting or misreporting of income — a mandatory legal threshold before any penalty can be levied.

Section 80GGC allows individual taxpayers to claim 100% of donations to registered political parties as a deduction, provided payment is made through banking channels — not cash above ₹2,000.

🎯 What You Should Do

Check if your political donation receipt is from an Election Commission-registered party and that payment was via cheque, UPI, or bank transfer — cash above ₹2,000 disqualifies the deduction entirely.

💡

File Section 80GGC deductions in your ITR with supporting documents saved digitally — if a notice arrives, respond within the deadline with your receipts and bank proof, do not ignore it.

If you receive a penalty notice on any deduction you legitimately claimed, consult a tax practitioner about filing an appeal — tribunals frequently delete penalties where the department's case is weak.

💡 Pro Tip

Pro tip: Under Section 80GGC, there is no upper rupee limit on the deduction for individuals — unlike Section 80G charity donations, which have caps. The only condition is non-cash payment.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
40 Crore Uninsured: Is Your Family Covered?
🛡️ Insurance
39d ago
💰
40 crore Indians

Your family could be among those with zero health cover — and one illness wipes savings

40 Crore Uninsured: Is Your Family Covered?

🤯 One hospitalisation in a metro can cost more than 3 years of a middle-class family's...

Read Full Story
📋 TL;DR

Over 40 crore Indians — mostly salaried workers and small business owners — have no health insurance. A single hospital stay can wipe out years of savings. Here's what the coverage gap means for your family and what you should do today.

📰 What Happened

More than 40 crore Indians — largely lower-middle and middle-income households — currently have no health insurance of any kind, creating a massive 'missing middle' coverage gap.

Parliamentary recommendations include creating an affordable health insurance product specifically for this income group, along with standardised hospital treatment costs to control claim inflation.

Employer-linked group health cover has been suggested as a key mechanism to reach salaried workers in small businesses who currently fall outside any formal insurance net.

🎯 What You Should Do

Check right now whether your employer provides group health insurance — if yes, verify the sum insured and whether your parents can be added as dependants.

💡

Compare family floater plans on IRDAI-registered aggregators: prioritise at least ₹5 lakh cover, a low co-payment clause, and hospitals near your home in the network list.

If you are a small business owner or freelancer, buy an individual or family floater plan this financial year — premiums paid are deductible under Section 80D up to ₹25,000 (₹50,000 for senior citizen parents).

💡 Pro Tip

Buy a base plan now while you are healthy — even a ₹3–5 lakh cover. Pre-existing conditions get covered after a 2–4 year waiting period only if the policy is active. Waiting until you are ill means permanent exclusions.

Insurance + loans sorted — one app for your money

Get GoCredit
SEBI's Digital KYC: NRIs Invest Without Flying Home?
📊 Investing
39d ago
💰
50 lakh+

NRIs who can now invest in Indian markets without flying home for paperwork

SEBI's Digital KYC: NRIs Invest Without Flying Home?

🤯 A Mumbai–London round trip costs ₹60,000+ — more than most NRIs invest per SIP cycle

Read Full Story
📋 TL;DR

SEBI wants to let NRIs and OCIs complete their investment KYC fully online from abroad, without visiting India. This could make it much easier and cheaper to invest in Indian mutual funds and stocks from overseas.

📰 What Happened

SEBI has proposed a fully digital KYC process for NRIs, OCIs, and eligible foreign nationals living in FATF-compliant countries who want to invest in Indian securities.

The proposal removes the requirement for any physical presence in India during the KYC process, replacing it with video-based or digitally verified identity checks.

SEBI also proposes making completed KYC records portable — usable across multiple brokers and mutual fund platforms without re-doing the process each time.

🎯 What You Should Do

Check if your country is on the FATF member list — if yes, you will likely qualify for this digital KYC process once it is finalised by SEBI.

💡

Review your existing NRE or NRO account status and talk to your bank or broker about updating your KYC documents now, before the new system launches.

Compare NRI-friendly investment platforms (Kuvera, MFCentral, HDFC Securities NRI desk) so you are ready to open or upgrade accounts the moment digital KYC goes live.

💡 Pro Tip

Pro tip: Even before this rule lands, NRIs can invest in Indian mutual funds via MFCentral using Aadhaar-based eKYC if they have a valid Indian mobile number linked to Aadhaar — no flight needed today.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
📈

Improve CIBIL by 100 Points

AI analyzes your report and gives a personalized action plan

Boost My Score
Hidden Foreign Assets? 100% Penalty Hits You Now
💰 Tax & Budget⚠️BORROWER ALERT
39d ago
📉
100% penalty

Hiding foreign income now costs you double — your asset plus full tax as penalty

Hidden Foreign Assets? 100% Penalty Hits You Now

🤯 That undisclosed ₹5L foreign account could cost you ₹10L+ — more than 8 months of a...

Read Full Story
📋 TL;DR

The government has launched a new disclosure scheme for small taxpayers with foreign assets. If you have undisclosed foreign income or assets, you must declare them or face a 100% penalty on top of your full tax dues. Ignoring this is very expensive.

📰 What Happened

CBDT has notified the Foreign Assets of Small Taxpayers–Disclosure Scheme, 2026, effective August 16, creating a formal window for declaring previously undisclosed foreign assets.

Eligibility is capped at ₹1 crore (and ₹5 crore for certain asset categories) in undisclosed foreign assets — taxpayers above these thresholds face prosecution under the Black Money Act.

Those who do not voluntarily disclose and are caught face a 100% penalty on the undisclosed asset value, in addition to the full tax and interest owed.

🎯 What You Should Do

Check all your foreign bank accounts, overseas property, foreign investments, or foreign gifts received — these must be disclosed in Schedule FA of your Indian ITR every year.

💡

If you have any undisclosed foreign asset below ₹1 crore, consult a qualified tax professional immediately about using this scheme before August 16 to avoid the 100% penalty.

Verify whether you have FATCA or CRS reporting obligations — India shares automatic tax data with 100+ countries, so assuming foreign accounts stay hidden is a dangerous bet.

💡 Pro Tip

Even small foreign accounts opened years ago during a job abroad or study trip must be reported in Schedule FA — ignorance is not a valid defence once CRS data flags your account.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
SCSS Maturing Soon? Extend It or Lose 8.2%
🏦 Savings & Deposits
39d ago
📉
8.2% per year

Your SCSS account earns this rate — but only if you renew it correctly

SCSS Maturing Soon? Extend It or Lose 8.2%

🤯 SCSS pays more quarterly interest than most FDs — enough to cover a family's monthly...

Read Full Story
📋 TL;DR

Senior Citizens Savings Scheme pays 8.2% per year with quarterly payouts. If your SCSS account is about to mature, you have two ways to extend it — but missing the deadline could mean losing interest for the gap period. Here's what to do.

📰 What Happened

SCSS accounts have a 5-year tenure and can be extended once for 3 additional years by submitting a written request within 1 year of maturity.

The government currently offers 8.2% per annum interest on SCSS, paid out every quarter — one of the highest guaranteed returns for retirees in India.

If a matured SCSS account is neither closed nor extended, the balance earns only the Post Office Savings Account rate until the holder acts on it.

🎯 What You Should Do

Check your SCSS passbook or account statement immediately to confirm your exact maturity date — plan your extension request at least 30 days in advance.

💡

Visit your post office branch or authorised bank and submit Form B (Extension Form) within 1 year of maturity to lock in the 3-year extension.

If you no longer need the income stream, compare premature closure rules versus reinvesting in a new SCSS account — couples can open separate accounts to double the ₹30 lakh deposit limit.

💡 Pro Tip

If you extend SCSS within 1 year of maturity, you can still close it prematurely after 1 year of the extended period with only a 1% penalty — giving you flexibility if rates change.

FD vs loan EMI — which earns you more? AI will tell

Compare Now
Loan Default? 5 Things Recovery Agents Can't Do
🏦 Bank Updates⚠️BORROWER ALERT
39d ago
60 days

Banks can label your loan an NPA this fast after you stop paying

Loan Default? 5 Things Recovery Agents Can't Do

🤯 A recovery agent who calls you at midnight is breaking RBI rules — not just being rude.

Read Full Story
📋 TL;DR

If you miss loan EMIs, banks have legal steps they must follow before seizing anything. Recovery agents also have strict limits. Know your rights before they knock on your door.

📰 What Happened

RBI mandates a 90-day overdue period before any loan is classified as a Non-Performing Asset, giving borrowers a legal window before serious recovery action begins.

Under the SARFAESI Act, banks must serve a 60-day written notice to secured-loan borrowers before physically seizing or taking possession of mortgaged property.

RBI's Fair Practices Code strictly regulates recovery agent behaviour — prohibited actions include late-night calls, intimidation, public shaming, and contacting family or employers without consent.

🎯 What You Should Do

Document every recovery agent interaction — save call logs, take screenshots of messages, and record any abusive calls as evidence for a formal complaint.

💡

File a written complaint with your bank's nodal grievance officer first; if unresolved within 30 days, escalate to RBI's Banking Ombudsman at cms.rbi.org.in at zero cost.

Check your loan agreement for the exact default and notice clause — then contact your lender immediately to negotiate a restructuring or moratorium before the 90-day NPA clock runs out.

💡 Pro Tip

Even after a SARFAESI seizure notice, you can pay the full dues and legally reclaim your property before auction — this redemption right is rarely communicated by lenders.

Is your bank safe? Check lender ratings on GoCredit

Check Lenders
Foreign Assets Under ₹5L? Disclose by Dec 2026
💰 Tax & Budget
39d ago
💰
₹5 lakh

Your undisclosed foreign assets must be below this to qualify for penalty relief

Foreign Assets Under ₹5L? Disclose by Dec 2026

🤯 The penalty for hiding foreign assets can hit 3x the asset value — more than most...

Read Full Story
📋 TL;DR

CBDT has launched a special disclosure scheme for small taxpayers with undisclosed foreign assets worth under ₹5 lakh. Declare by December 31, 2026 to avoid massive penalties under the Black Money Act.

📰 What Happened

CBDT has officially notified rules for the Foreign Assets of Small Taxpayers disclosure scheme, with a deadline of December 31, 2026.

The scheme covers Indian taxpayers with undisclosed foreign assets totalling below ₹5 lakh — think dormant overseas accounts, unclaimed ESOPs, or old PayPal balances.

Under India's Black Money Act 2015, failing to disclose foreign assets can attract a penalty of up to 3 times the asset value plus a flat 30% tax with zero deductions.

🎯 What You Should Do

Check all overseas accounts, foreign ESOPs, PayPal/Wise balances, and inherited foreign property — list everything before October 2026 to give yourself filing time.

💡

File your ITR Schedule FA (Foreign Assets) correctly for AY 2025-26 — even small omissions in this schedule can trigger scrutiny under the Black Money Act.

Consult a CA experienced in FEMA and Black Money Act compliance before using this scheme — incorrect disclosure can sometimes create more liability than it resolves.

💡 Pro Tip

Foreign ESOPs vested while working abroad are reportable even if you never sold them. Their fair market value on the vesting date counts as a foreign asset in Schedule FA.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
Foreign Assets Undisclosed? Declare by Dec 31 or Pay ₹10L
💰 Tax & Budget
39d ago
💰
₹10 lakh penalty waived

Declare your foreign assets now — or face a ₹10 lakh minimum fine later

Foreign Assets Undisclosed? Declare by Dec 31 or Pay ₹10L

🤯 ₹10 lakh minimum penalty = 83 months of a ₹12K salary — just for not telling the...

Read Full Story
📋 TL;DR

The government has opened a one-time window for Indian taxpayers to voluntarily disclose foreign assets they forgot or didn't report earlier. Declare by December 31, 2026, and avoid massive Black Money Act penalties. Missing this deadline could cost you ₹10 lakh or more.

📰 What Happened

The Indian government has opened a one-time voluntary disclosure window for taxpayers to declare previously unreported foreign assets, open until December 31, 2026.

The scheme targets individuals who hold overseas bank accounts, foreign stocks, property abroad, or other foreign assets not declared in Schedule FA of their Income Tax Return.

Taxpayers who disclose proactively get protection from heavy Black Money Act penalties — which start at ₹10 lakh per undisclosed asset — and potential prosecution.

🎯 What You Should Do

Open your last 3 ITRs and check Schedule FA — if any foreign bank account, overseas shares, or inherited property abroad is missing, you need to act before December 31, 2026.

💡

File a revised or updated ITR (ITR-U) to include the missing foreign asset disclosure; consult a CA experienced in Black Money Act compliance to ensure the declaration is correctly structured.

Calculate and pay any base income tax owed on income earned from the foreign asset — the window waives penalties and prosecution risk, but the underlying tax liability still applies.

💡 Pro Tip

Even a dormant foreign bank account with zero balance must be declared in Schedule FA every year — 'no activity' is not a valid exemption under the Black Money Act.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
💰

Compare EMI Across 100+ Lenders

Same loan, different EMI. Find which lender saves you the most

Compare Now
Foreign Asset Amnesty 2026: What You Must Declare
💰 Tax & Budget
39d ago
💰
₹1 crore

Your undisclosed foreign assets above this limit face steeper penalties

Foreign Asset Amnesty 2026: What You Must Declare

🤯 Hiding ₹1L abroad can cost more in penalties than 2 years of your Mumbai rent.

Read Full Story
📋 TL;DR

India's Foreign Assets Disclosure Scheme opens August 16, 2026, letting people voluntarily declare hidden overseas assets by December 31, 2026. Miss the deadline and face criminal prosecution under the Black Money Act — not just a fine.

📰 What Happened

India launched a voluntary Foreign Assets Disclosure Scheme effective August 16, 2026, allowing residents to declare previously unreported overseas assets by December 31, 2026.

All asset values under the scheme are computed as of March 31, 2026, meaning the government has set a fixed valuation date that declarants cannot manipulate.

Assets above the ₹1 crore threshold face distinct tax and penalty treatment under the Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015.

🎯 What You Should Do

Check your ITR filings for the last 5 years — if you held any foreign bank account, property, or share in a foreign company and did not report it in Schedule FA, you need to act before August 16.

💡

Consult a CA or tax lawyer specialising in international taxation immediately to compute your March 31, 2026 asset value and determine your exact tax liability under the scheme.

Avoid waiting until December — disclosure windows tend to get crowded near the deadline, and a rushed filing with errors could be treated as incomplete, leaving you exposed.

💡 Pro Tip

Even a small foreign savings account opened during a work visa abroad counts as a foreign asset under FEMA and must be declared. Many salaried returnees miss this and are unknowingly non-compliant.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
₹5 Lakh to Invest? Your Age Changes Everything
📋 Financial Planning
39d ago
💰
₹5 Lakh

How you invest this amount today can double — or halve — your wealth in 10 years

₹5 Lakh to Invest? Your Age Changes Everything

🤯 ₹5 lakh kept in a savings account for 10 years loses roughly ₹1.2 lakh in real value...

Read Full Story
📋 TL;DR

Got ₹5 lakh to invest? Where you put it should depend on your age, income, and goals — not just which option sounds safe. Here's a practical, age-smart breakdown.

📰 What Happened

A lump sum of ₹5 lakh is a significant savings milestone for most Indian middle-class households — but where to put it depends heavily on age, goals, and existing financial commitments.

Younger investors (20s) can lean heavily into equity mutual funds for long-term compounding, while those in their 40s need to prioritise capital safety, liquidity, and debt reduction.

Asset allocation — splitting money across equity, debt, gold, and liquid instruments — is the single most important decision that determines whether ₹5 lakh grows or stagnates over a decade.

🎯 What You Should Do

Check your current age bracket and map your ₹5 lakh split: 20s → 70% equity SIP + 20% PPF + 10% liquid; 30s → 50% equity + 20% FD/debt + 20% PPF + 10% liquid; 40s+ → 40% hybrid funds + 30% FD/PPF + 20% gold + 10% liquid.
💡

Start a SIP instead of investing the full ₹5 lakh as a lump sum — spread it over 10-12 months via a systematic transfer plan (STP) from a liquid fund to reduce timing risk.

Before investing, clear any high-interest personal loan or credit card debt above 14% — guaranteed returns from debt reduction beat most market instruments risk-adjusted.

💡 Pro Tip

Sovereign Gold Bonds (SGBs) give you gold's price upside PLUS 2.5% annual interest, and long-term capital gains are completely tax-free if you hold until the 8-year maturity — most investors miss this.

AI finds your cheapest loan from 100+ lenders

Explore Smart Investment Options
IDFC First Bank Rated Investment Grade
🏦 Bank Updates
39d ago
💰
₹10,000+ crore

Your IDFC First Bank deposits just got a stronger safety signal

IDFC First Bank Rated Investment Grade — Aug 2026

🤯 An investment-grade rating costs banks less to borrow — which can mean slightly better...

Read Full Story
📋 TL;DR

S&P Global has given IDFC First Bank an investment-grade credit rating, reflecting stronger profits and better capital health. For everyday customers, this means your deposits and savings at the bank sit on firmer ground than before.

📰 What Happened

S&P Global Ratings assigned IDFC First Bank an investment-grade credit rating, reflecting improved financial stability and capital strength.

The rating agency credited the bank's consistent capital-raising efforts, rising profitability, and a low dividend payout that retains earnings within the bank.

IDFC First Bank, formed from the 2018 merger of IDFC Bank and Capital First, has steadily grown its retail deposit franchise and loan book over the past five years.

🎯 What You Should Do

Check whether your total deposits at IDFC First Bank exceed ₹5 lakh — DICGC insurance covers only up to that limit per bank regardless of its credit rating.

💡

Compare IDFC First Bank's current FD rates against peer private banks; a stronger credit profile can sometimes translate into competitive deposit offers worth locking in.

Review your overall bank diversification — spread large savings across at least two or three scheduled commercial banks to stay within the insured limit at each.

💡 Pro Tip

DICGC deposit insurance covers ₹5 lakh per depositor per bank — not per account. Multiple accounts at the same bank share one ₹5 lakh ceiling.

Is your bank safe? Check lender ratings on GoCredit

Check Lenders
Hidden Foreign Assets? Pay 60% Tax, Stay Safe
💰 Tax & Budget
39d ago
📉
60% tax — then full immunity

Pay this on your hidden foreign assets and escape all penalties forever

Hidden Foreign Assets? Pay 60% Tax, Stay Safe

🤯 Forgetting to declare a foreign bank account can cost more than 10 years of chai money...

Read Full Story
📋 TL;DR

CBDT has launched a one-time window for small taxpayers to come clean about undisclosed foreign income or assets. Declare by December 2026, pay 60% of the asset value as tax, and get full immunity from penalties and prosecution.

📰 What Happened

CBDT launched a one-time foreign asset disclosure scheme on 16 August 2025, open until December 2026, allowing small taxpayers to declare undisclosed overseas income and assets.

Taxpayers who voluntarily disclose must pay 60% of the declared foreign asset or income value as tax — this payment grants full immunity from penalties and criminal prosecution.

India exchanges financial account data with over 100 countries under FATCA and CRS, meaning CBDT may already have information on foreign accounts held by Indian residents.

🎯 What You Should Do

Check your ITR's Schedule FA — if you hold or held any foreign bank account, property, or investment and haven't declared it, you may already be non-compliant and should consult a tax advisor immediately.

💡

Gather documents for any overseas asset — account statements, property deeds, or inheritance records — before approaching a CA to assess whether this disclosure window applies to you.

Avoid waiting until December 2026 — if CBDT's FATCA or CRS data flags your account before you disclose, you lose immunity and face the full 300% penalty under the Black Money Act.

💡 Pro Tip

Even a dormant foreign account with ₹0 balance must be declared in Schedule FA of your ITR if it was held at any point during the financial year — non-disclosure is a violation regardless of the balance.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
CRED's NBFC Arm Grows 156%: Is Your Instant Loan Safe?
📱 Fintech News
39d ago
💰
₹4,582 crore

CRED-backed NBFC's loan book — here's what instant credit apps mean for you

CRED's NBFC Arm Grows 156%: Is Your Instant Loan Safe?

🤯 ₹4,582 crore in loans — that's enough to pay 1.5 lakh families' monthly grocery bills...

Read Full Story
📋 TL;DR

CRED-backed NewTap Finance has grown its loan book at a stunning 156% CAGR since FY23. Before you tap 'instant loan' on any fintech app, here's what you need to know about NBFC lending, your rights, and hidden risks.

📰 What Happened

CRED-backed NewTap Finance, an RBI-registered NBFC, grew its managed loan portfolio to ₹4,582 crore in FY26, expanding at roughly 156% CAGR since FY23.

The NBFC's total income nearly doubled year-on-year, reflecting rapid growth in instant, app-based personal lending to salaried and creditworthy Indian consumers.

CRISIL Ratings assessed NewTap's financials, highlighting improved return on assets — signalling that fast-growing fintech NBFCs are becoming a mainstream source of personal credit in India.

🎯 What You Should Do

Verify any NBFC offering you a loan is RBI-registered — check the 'List of NBFCs' on rbi.org.in before accepting any instant loan offer from a fintech app.

💡

Compare the annualised interest rate (APR) on any app-based loan against your bank's personal loan rate — fintech NBFC rates can be 2x to 3x higher for the same loan amount.

Read your loan sanction letter carefully to identify who the actual lender is — in managed AUM structures, the app you see and the NBFC actually holding your loan may be different entities.

💡 Pro Tip

If your fintech lender transfers your loan to another NBFC mid-tenure, you must receive written notice — file a complaint with RBI's Sachet portal if you don't.

AI finds your cheapest loan from 100+ lenders

Compare Loan Rates Now
📊

Free CIBIL Score Check

Check your credit score instantly — zero impact on CIBIL

Check Score Free
₹30,000 Min Wage Push: How Your EPF & Pay Change?
📋 Financial Planning
39d ago
💰
₹30,000

Proposed minimum monthly wage that could reshape your take-home and EPF contributions

₹30,000 Min Wage Push: How Your EPF & Pay Change?

🤯 ₹30,000/month minimum wage = 300 cups of café coffee daily — yet millions earn half...

Read Full Story
📋 TL;DR

A major trade union is demanding ₹30,000 minimum monthly wage, higher EPF wage ceiling, and better pensions before an August 17 strike. If accepted, it could change how much you and your employer contribute to EPF — and what pension you eventually receive.

📰 What Happened

A major trade union has announced a nationwide strike on August 17, demanding the monthly minimum wage for unskilled workers be raised to ₹30,000.

Key demands include hiking the EPF wage ceiling (currently ₹15,000/month) and raising the ESIC wage threshold so more workers access subsidised health coverage.

Unions are also pushing for stronger job security protections for contract and gig workers and a significant increase in pension payouts under existing schemes.

🎯 What You Should Do

Check your EPF passbook on the EPFO portal — confirm whether your employer is contributing on your actual basic salary or only on the ₹15,000 statutory ceiling.

💡

Calculate how much more your retirement corpus would grow if EPF contributions were made on your full basic pay — use the EPFO online pension calculator.

If you are a contract or gig worker, review whether you currently qualify for ESIC coverage and register immediately if your gross wage is under ₹21,000/month.

💡 Pro Tip

Even without a ceiling hike, you can voluntarily contribute more via VPF (Voluntary Provident Fund) at the same 8.25% tax-free interest rate — no employer approval needed.

AI finds your cheapest loan from 100+ lenders

Check Your EPF Balance
Big FD Portfolio? 3 Tax Rules Draining Your Returns
🏦 Savings & Deposits
39d ago
📉
30% tax

Your FD interest could be taxed at this rate if you're not careful

Big FD Portfolio? 3 Tax Rules Draining Your Returns

🤯 ₹7L FD interest can cost you more tax than 6 months of chai and auto fares combined.

Read Full Story
📋 TL;DR

Fixed deposits are popular in India, but many people don't realise how much tax they quietly pay on FD interest. Here's how FD taxation works, what TDS means for you, and how to legally reduce your tax burden on large FD portfolios.

📰 What Happened

FD interest in India is fully taxable as 'Income from Other Sources' at the investor's applicable income tax slab rate, with no flat concessional rate.

Banks are required to deduct TDS at 10% once your total FD interest from that bank exceeds ₹40,000 per year (₹50,000 for senior citizens) under Section 194A.

Large FD portfolios — running into several crores — can generate interest income in lakhs annually, pushing the investor into the highest 30% tax bracket on that income.

🎯 What You Should Do

Check your Form 26AS on the Income Tax portal to verify how much TDS has already been deducted from your FD interest this financial year.

💡

Submit Form 15G (or Form 15H if you are a senior citizen) to your bank at the start of each April if your total income is below the taxable threshold — this prevents unnecessary TDS deduction.

Consider splitting large lump-sum FD investments between your name and a spouse or parent (with their own income sources) to avoid all interest being taxed at a single high slab rate.

💡 Pro Tip

Interest from tax-saving FDs (5-year lock-in under Section 80C) qualifies for a deduction up to ₹1.5 lakh — but the interest earned on them is still fully taxable. Many investors miss this and get a surprise tax bill.

FD vs loan EMI — which earns you more? AI will tell

Compare Now
Insurer Denied ₹1Cr Claim — Court Forced Them to Pay
🛡️ Insurance
39d ago
💰
₹1 crore denied

Your family's claim can be rejected if you hide any insurance detail

Insurer Denied ₹1Cr Claim — Court Forced Them to Pay

🤯 A ₹1 crore term plan costs less than ₹800/month — but one missed disclosure can erase...

Read Full Story
📋 TL;DR

A widow's ₹1 crore life insurance claim was initially rejected for alleged non-disclosure. The court ruled in her favour. Here's what every policyholder must know to protect their family from the same fate.

📰 What Happened

A life insurer rejected a widow's ₹1 crore claim alleging the deceased husband had not disclosed prior insurance details on his proposal form.

The court ruled against the insurer, finding that the company had failed to conduct proper due diligence before issuing the policy and could not reject the claim post-death on the same grounds.

The case highlights a growing pattern where Indian courts are holding insurers accountable when they accept premiums without verifying disclosures, then use those gaps to deny claims.

🎯 What You Should Do

Disclose every existing life insurance policy, health condition, and hospitalisation history honestly on your proposal form — even if an agent tells you to skip it.

💡

Check your policy's date of issuance: if it is more than 2 years old and no investigation was initiated, the insurer's grounds for non-disclosure rejection become legally weak under Section 45 of the Insurance Act.

If a claim is rejected in your family, immediately request the written repudiation letter with specific legal grounds, then approach the Insurance Ombudsman — it is free and typically resolves within 3 months.

💡 Pro Tip

Under Section 45 of the Insurance Act, a policy cannot be called into question after 3 years of being in force on any grounds whatsoever — making older policies nearly claim-proof.

Insurance + loans sorted — one app for your money

Get GoCredit
Insurtech Stocks Surge: Is Your Policy Wallet-Smart?
🛡️ Insurance
39d ago
📉
22.64% surge

Turtlemint's stock jump signals your insurance buying habits are shifting fast

Insurtech Stocks Surge: Is Your Policy Wallet-Smart?

🤯 Indians spend more on chai annually than on term life insurance — and insurtech is...

Read Full Story
📋 TL;DR

Insurance tech companies like Turtlemint are seeing big stock gains as more Indians buy policies online. This means cheaper, faster, and more transparent insurance is coming — but you still need to know what to look for before clicking 'buy'.

📰 What Happened

Insurtech platform Turtlemint's stock rose over 22% in a single week, reflecting strong investor confidence in digital insurance distribution in India.

India's new-age tech stock segment saw 30 companies gain this week, driven by Q1 FY27 earnings season results and forward business guidance.

The insurtech sector is growing as more Indians research and purchase health, term life, and motor insurance policies through online platforms rather than agents.

🎯 What You Should Do

Compare your current health or term plan on at least 2 IRDAI-regulated aggregator platforms to check if you are overpaying on premium for the same cover.

💡

Check the claim settlement ratio of your insurer — any ratio below 95% should make you reconsider at renewal time; IRDAI publishes this data annually.

Review your policy document's exclusions section before your next renewal — digital platforms make buying easy but most buyers never read what is NOT covered.

💡 Pro Tip

Pro tip: IRDAI mandates that insurance web aggregators display products from multiple insurers — if a site only shows one brand prominently, request a full comparison before purchasing.

Insurance + loans sorted — one app for your money

Get GoCredit
₹5L to ₹1.3 Cr in 7 Years: Can You Copy It?
📊 Investing
39d ago
🎯
26x growth in 7 years

Your ₹5 lakh can realistically grow to ₹1.30 crore with time and discipline

₹5L to ₹1.3 Cr in 7 Years: Can You Copy It?

🤯 ₹5 lakh invested in 2017 = ₹1.30 crore today. That's 43 years of chai at ₹25/day —...

Read Full Story
📋 TL;DR

An Indian retail investor grew a ₹5 lakh portfolio to ₹1.30 crore in seven years through SIPs, mistake-driven learning, and staying invested during market crashes. Here's what that journey actually looks like — and what you can take from it.

📰 What Happened

A retail investor grew a ₹5 lakh starting portfolio to ₹1.30 crore over seven years, primarily through equity mutual funds and disciplined SIP investing.

The journey included costly early mistakes — wrong fund choices, panic during crashes, over-diversification — which became the actual learning curve that shaped the final strategy.

The bulk of wealth creation happened in the later years of the journey, demonstrating the classic back-loaded nature of compounding that most investors abandon too early.

🎯 What You Should Do

Calculate your current SIP's projected corpus using a SIP calculator at 12% CAGR over 7, 10, and 15 years — if the number doesn't excite you, increase your monthly amount now.

💡

Check your portfolio for funds you've held less than 3 years and haven't reviewed — if you bought on a tip or theme, evaluate whether the fundamentals still hold.

Set a written rule today for your next market crash: a specific % drop (e.g., Nifty falls 15%) triggers a lump-sum top-up, not a redemption — commit to it before the crash happens.

💡 Pro Tip

Pro tip: Step-up your SIP by just 10% every April (after salary hike). On a ₹5,000/month SIP, that single habit adds over ₹15 lakh extra corpus over 10 years at 12% returns.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
🎯

AI Loan Agent — 100+ Lenders

AI scans all lenders and finds your cheapest EMI automatically

Find Cheapest Loan
EPF Membership: 5 Rules Your Employer Won't Tell You
📋 Financial Planning
39d ago
💰
₹7,500/month

Your employer must enrol you in EPF once your salary crosses this threshold

EPF Membership: 5 Rules Your Employer Won't Tell You

🤯 EPF's 8.25% interest beats most FDs — yet crores of eligible workers never get enrolled.

Read Full Story
📋 TL;DR

If your basic salary is ₹15,000 or less, your employer must enrol you in EPF by law. But many workers miss out due to ignorance or employer non-compliance. Here's everything you need to know about joining, contributing, and protecting your EPF account.

📰 What Happened

EPF membership is mandatory for every employee earning a basic salary of ₹15,000 or less per month in any establishment covered under the Employees' Provident Funds Act, 1952.

Establishments with 20 or more employees across most sectors — including factories, retail, IT firms, and private schools — are legally required to register with EPFO and enrol eligible staff.

EPF currently offers an interest rate of 8.25% per annum for FY2023-24, credited annually to members' accounts, making it one of the highest guaranteed returns available to Indian salaried workers.

🎯 What You Should Do

Check your salary slip today — if your basic pay is ₹15,000 or below and your employer hasn't enrolled you in EPF, raise a written complaint with your HR or file a grievance at epfigms.gov.in.

💡

Activate your Universal Account Number (UAN) on the EPFO member portal (unifiedportal-mem.epfindia.gov.in) and link your Aadhaar, PAN, and bank account to ensure smooth withdrawals and transfers.

If you switch jobs, use the EPFO online transfer facility to consolidate old PF accounts into your current UAN — don't leave dormant accounts idle, as unclaimed funds may be transferred to the Senior Citizens' Welfare Fund after 7 years.

💡 Pro Tip

Even if your basic salary exceeds ₹15,000, you can voluntarily contribute on your actual salary — this boosts your retirement corpus significantly since 8.25% compounded over 20-30 years dwarfs most market-linked options.

AI finds your cheapest loan from 100+ lenders

Check Your EPF Balance
UPI Hits 23B Transactions
📱 Fintech News
39d ago
🎯
23.66 billion

UPI transactions hit this record — your payments app choice now matters more than ever

UPI Hits 23B Transactions — Aug 2026

🤯 23.66 billion UPI transactions in one month — that's roughly 280 payments fired every...

Read Full Story
📋 TL;DR

UPI crossed 23.66 billion transactions in July 2025, a new high. PhonePe leads, Google Pay follows, and Paytm is third. Here is what this boom means for your daily payments, cashback rewards, and financial safety.

📰 What Happened

UPI recorded 23.66 billion transactions in July 2025, the highest monthly volume in the payment system's history.

PhonePe extended its lead as India's top UPI app by transaction count, with Google Pay holding second position.

Paytm's UPI transaction volume recovered to 1.90 billion in July from 1.80 billion in June, signalling a gradual rebound.

🎯 What You Should Do

Compare cashback and reward programs across PhonePe, Google Pay, and Paytm — even ₹200–₹300 monthly savings add up to ₹2,400–₹3,600 a year.

💡

Check that your UPI-linked bank account is active and your mobile number is correctly registered — stale links cause failed transactions and can delay emergency payments.

Enable UPI transaction alerts and set a daily transaction limit inside your payments app settings to protect yourself from unauthorised debits during high-fraud months.

💡 Pro Tip

You can link multiple bank accounts to a single UPI app and set different accounts as default for different types of payments — keeping your salary account separate from your daily spending account reduces fraud exposure significantly.

AI finds your cheapest loan from 100+ lenders

Compare Payment Apps Now
ETF Tracking Error: Is Your Index Fund Lying?
📊 Investing
40d ago
📉
2.5% gap

Your ETF can silently lag its index by this much every year

ETF Tracking Error: Is Your Index Fund Lying?

🤯 A 1.5% annual tracking error on ₹5L ETF investment costs you ₹7,500/year — that's 125...

Read Full Story
📋 TL;DR

Not all ETFs perfectly copy their index. Tracking error measures how much your ETF drifts from its benchmark. A high tracking error means you're paying for index returns but getting something worse. Here's how to check before you invest.

📰 What Happened

Tracking error measures how consistently an ETF mirrors its benchmark index — it is the standard deviation of monthly return differences between the ETF and its index.

A high tracking error means your ETF swings away from the index unpredictably, even if the average annual gap looks small on paper.

Indian sectoral and mid-cap ETFs often show tracking errors of 1–2.5% annually, while large-cap Nifty 50 ETFs from major AMCs typically stay below 0.5%.

🎯 What You Should Do

Check both tracking error AND tracking difference for any ETF you hold or plan to buy — use AMC factsheets or screeners updated monthly.

💡

Compare at least 3 ETFs tracking the same index before investing — choose the one with the lowest tracking error AND lowest expense ratio combined.

Avoid ETFs with low AUM (below ₹500 crore) since thin liquidity worsens tracking error through wider bid-ask spreads and cash drag.

💡 Pro Tip

Tracking difference (annual total return gap vs index) is more actionable than tracking error alone — an ETF can be consistent but still consistently underperform. Always check both numbers.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
FIRE Movement: Can You Retire Before 45 in India?
📋 Financial Planning
40d ago
🎯
25x annual expenses

Your FIRE corpus target — most Indians wildly underestimate this number

FIRE Movement: Can You Retire Before 45 in India?

🤯 Saving ₹500/day from age 25 compounds to ₹1.2 crore by 45 — that's just chai money...

Read Full Story
📋 TL;DR

Financial Independence, Retire Early (FIRE) is catching on with young Indians — but building a corpus big enough to never work again takes serious planning, the right number, and more than just quitting your job.

📰 What Happened

FIRE (Financial Independence, Retire Early) is gaining traction among Indian millennials and Gen Z professionals seeking to exit the traditional 35-year work grind before age 45.

True financial independence in India requires a corpus of at least 25–33 times your annual expenses, accounting for 6%+ inflation and potentially 40 years of post-retirement life.

Many early FIRE aspirants overlook healthcare costs, family obligations, and the psychological challenge of stepping away from structured work — making the transition harder than the math alone.

🎯 What You Should Do

Calculate your real FIRE number: multiply your current annual household expenses by 33 (not 25) to account for Indian inflation and a 40-year retirement horizon.

💡

Buy a comprehensive personal health insurance policy of at least ₹25–50 lakh NOW — before you leave employment, while you still have no claim history and lower premiums.

Stress-test your portfolio against a 30% equity market crash and 7% inflation simultaneously using a free SIP and withdrawal calculator — if it runs dry before age 80, your corpus is too small.

💡 Pro Tip

Park your FIRE corpus across three buckets — 2 years' expenses in liquid funds, 8 years in debt funds, and the rest in equity — so a market crash never forces you to sell equities at a loss to pay rent.

AI finds your cheapest loan from 100+ lenders

Plan Your FIRE Journey
₹7.5 Cr Net Worth Rule: Can You Access Elite Investments?
📊 Investing🔴BREAKING NEWS
40d ago
💰
₹7.5 crore net worth

The threshold that could unlock exclusive high-return investment products for you

₹7.5 Cr Net Worth Rule: Can You Access Elite Investments?

🤯 ₹7.5 crore is roughly 150 years of the average Indian salaried employee's annual...

Read Full Story
📋 TL;DR

SEBI is reviewing who qualifies as an 'Accredited Investor' — a special status that lets wealthy individuals invest in high-return products not available to regular investors. If rules change, more Indians could qualify and access better investment options.

📰 What Happened

SEBI has released a consultation paper proposing a review of the Accredited Investor Framework, which defines who can access exclusive, lightly regulated investment products.

Currently, an individual needs ₹7.5 crore in net worth or ₹1 crore annual income to earn Accredited Investor status — thresholds set when the framework launched in 2021.

SEBI is inviting public comments to potentially widen eligibility or adjust criteria, which could allow more affluent middle-class Indians to access premium investment avenues.

🎯 What You Should Do

Check if your net worth or annual income is near the ₹7.5 crore or ₹1 crore thresholds — a revised framework could make you eligible sooner than you think.

💡

Submit your feedback on SEBI's consultation portal at sebi.gov.in before the public comment deadline — your input can genuinely influence the final rule change.

Explore what Accredited Investor products like AIFs, PMS, and structured products offer now, so you can plan your investments if the eligibility bar drops.

💡 Pro Tip

Accredited Investor certification in India is issued by SEBI-registered depositories like NSDL and CDSL — once certified, it's valid for one year and must be renewed annually.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
🛡️

Recovery Harassment? Get Help

Loan Kavach: legal team fights harassment calls for you

Get Protection
Silver Drops 1.4%: Should You Buy the Dip Now?
📊 Investing
40d ago
💰
₹95,000/kg

Silver in India costs this much — and your entry point matters

Silver Drops 1.4%: Should You Buy the Dip Now?

🤯 1 kg of silver today buys roughly 4,750 cups of cutting chai — not bad for a 'cheap'...

Read Full Story
📋 TL;DR

Silver prices fell about 1.4% globally and in India too. Should you buy now or wait? Here's what drives silver prices and what Indian investors should actually do with this dip.

📰 What Happened

Silver prices fell nearly 1.4% on COMEX as investors booked profits after a recent rally, with Indian domestic prices dropping in tandem.

US monetary policy uncertainty, a firm dollar, and cautious industrial demand from China weighed on silver's short-term outlook.

India's silver prices are also influenced by import duties and the rupee-dollar exchange rate, which can widen or narrow the impact of global price swings.

🎯 What You Should Do

Check the gold-silver ratio before buying: if it's above 80, silver is historically cheap relative to gold — consider adding small quantities via Sovereign Gold Bond alternatives or silver ETFs.

💡

Avoid buying physical silver bars or coins impulsively during a dip — factor in making charges, GST (3%), and storage costs, which eat into your returns significantly.

Set a target allocation — silver should not exceed 5-10% of your overall investment portfolio; use SIP-style purchases in silver ETFs to average out your cost over 6-12 months.

💡 Pro Tip

Silver ETFs listed on NSE and BSE let you invest in silver without GST on purchase, no storage headache, and full price transparency — far better than physical coins for most retail investors.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
EPF's 8.25% Return: Is Your Retirement Safe?
📋 Financial Planning
40d ago
📉
8.25% tax-free

Your EPF earns this rate — compounded, guaranteed, and completely tax-free at withdrawal

EPF's 8.25% Return: Is Your Retirement Safe?

🤯 Skipping EPF for 5 years can cost you ₹15L+ by retirement — that's 1,500 cups of chai...

Read Full Story
📋 TL;DR

EPF is one of India's safest retirement tools — it gives 8.25% tax-free interest with employer matching. But early withdrawals and job gaps quietly destroy the compounding effect most salaried workers never see coming.

📰 What Happened

EPFO kept the EPF interest rate at 8.25% for FY2024-25, making it one of the highest guaranteed returns among debt instruments available to salaried Indians.

Both employee and employer contribute 12% of basic salary each — employee's full share goes to EPF, while most of the employer's share funds the pension scheme (EPS).

EPF withdrawals before 5 years of continuous service attract full income tax, including TDS at 10% if the withdrawal exceeds ₹50,000 — a trap many job-hoppers fall into.

🎯 What You Should Do

Transfer your old EPF account to your new employer's account online at the EPFO Unified Member Portal (unifiedportal-mem.epfindia.gov.in) within 60 days of joining a new job.

💡

Check your EPF passbook annually on the EPFO portal or UMANG app to verify that your employer is depositing contributions on time — delays are common and reduce your compounding.

Avoid partial EPF withdrawals for non-emergency reasons like weddings or gadgets — even partial withdrawals restart the 5-year tax-free clock on that portion of your corpus.

💡 Pro Tip

Opt for Voluntary Provident Fund (VPF) contributions above the mandatory 12% — it earns the same 8.25% tax-free rate with zero market risk, and contributions qualify for Section 80C deduction.

AI finds your cheapest loan from 100+ lenders

Plan Your Retirement Now
₹5L Health Cover for Pensioners: Is Yours Enough?
🛡️ Insurance
40d ago
💰
₹5 lakh/year

Your cashless health cover limit if you're a Karnataka government pensioner

₹5L Health Cover for Pensioners: Is Yours Enough?

🤯 ₹5 lakh sounds big — but one heart surgery in Bengaluru easily crosses ₹8–12 lakh today.

Read Full Story
📋 TL;DR

Karnataka launched the Sandhya Kiran cashless health scheme for state government pensioners. It covers up to ₹5 lakh per year, and pensioners contribute to it. Here's what it means for your healthcare wallet in retirement.

📰 What Happened

Karnataka state government launched the Sandhya Kiran cashless health insurance scheme specifically for state government pensioners and their eligible dependants.

The scheme provides up to ₹5 lakh in annual cashless hospitalisation cover, usable at empanelled government and private hospitals across Karnataka.

Unlike fully funded schemes, Sandhya Kiran is contributory — pensioners are required to pay a portion of the premium, with the government sharing the remaining cost.

🎯 What You Should Do

Check your annual pension slip or contact your district treasury office to confirm your contribution amount and enrolment status under Sandhya Kiran.

💡

Compare the ₹5 lakh cover against your actual healthcare risk — if you have a chronic condition, buy a ₹10–15 lakh super top-up policy to plug the gap affordably.

Verify the list of empanelled hospitals in your city before any planned procedure, so you can access cashless treatment without paperwork delays.

💡 Pro Tip

A super top-up health plan activates only when your base cover is exhausted — pairing ₹5 lakh government cover with a ₹15 lakh super top-up costs far less than buying ₹20 lakh standalone senior cover.

Insurance + loans sorted — one app for your money

Get GoCredit
Travel Abroad? Your Health Cover Stops at the Border
🛡️ Insurance
40d ago
💰
₹0 covered abroad

Your Indian health insurance pays nothing once you leave the country

Travel Abroad? Your Health Cover Stops at the Border

🤯 One overseas hospital night can cost more than 6 months of your home rent.

Read Full Story
📋 TL;DR

Most Indians don't know their domestic health insurance is useless abroad. International travel insurance fills this gap — covering medical emergencies, trip cancellations, and lost baggage when you fly overseas. Here's what to look for before you buy.

📰 What Happened

Galaxy Health Insurance has launched an international travel insurance product targeting Indians travelling overseas for leisure, business, or education purposes.

The product covers overseas medical emergencies, trip cancellations, baggage loss, and passport-related issues, with global assistance handled through a partnership with Europ Assistance India.

This launch adds another player to India's growing travel insurance segment, giving consumers more options to compare alongside existing products from Bajaj Allianz, Tata AIG, and HDFC Ergo.

🎯 What You Should Do

Check your existing health insurance policy document — look for a 'geographical scope' or 'territorial limits' clause to confirm it does NOT cover overseas medical treatment.

💡

Compare international travel insurance plans on IRDAI-regulated aggregator platforms before your next trip — compare sum insured, medical evacuation cover, and pre-existing disease exclusions across at least 3 insurers.

If you are applying for a Schengen visa, verify your policy explicitly meets the €30,000 minimum medical cover requirement and that the insurer is accepted by the relevant embassy.

💡 Pro Tip

Always buy travel insurance with a cashless hospitalisation network abroad — reimbursement claims for overseas treatment require you to pay first in foreign currency, which most travellers cannot afford in a crisis.

Insurance + loans sorted — one app for your money

Get GoCredit
Gen Z Earns More — But Saves Less Than You Think?
📋 Financial Planning
40d ago
💰
₹18,000/month

Average discretionary spend eating into your savings every month

Gen Z Earns More — But Saves Less Than You Think?

🤯 Gen Z spends more on food delivery in a month than most Indians earn in a week.

Read Full Story
📋 TL;DR

New salary data on 5 lakh+ Indian earners shows Gen Z spends heavily on lifestyle but often skips basic savings habits. Here's what the numbers reveal — and what young earners should actually be doing with their money.

📰 What Happened

Spending data from over 5 lakh salaried Indians shows Gen Z allocates a disproportionately large share of income to lifestyle categories like food delivery, subscriptions, and fashion.

Despite higher starting salaries than previous generations, young earners show savings rates of 8–12%, significantly below the recommended 20% threshold for financial security.

Discretionary EMIs — on smartphones, gadgets, and buy-now-pay-later purchases — are quietly locking a large chunk of Gen Z income into fixed monthly outflows before savings happen.

🎯 What You Should Do

Automate your SIP or RD transfer on the same day your salary lands — treat it like a bill, not an afterthought.

💡

Audit your subscriptions and BNPL EMIs this weekend: list every monthly commitment and cancel anything unused for 30+ days.

Set a hard 'lifestyle cap' — cap discretionary spending (food, shopping, entertainment) at 30% of take-home and track it weekly using any free UPI statement export.

💡 Pro Tip

Pro tip: Splitting salary into two accounts — one for fixed bills, one for spending — reduces impulse overspend by up to 25% without requiring any willpower or budgeting app.

AI finds your cheapest loan from 100+ lenders

Build Your Savings Plan
📈

Improve CIBIL by 100 Points

AI analyzes your report and gives a personalized action plan

Boost My Score
NRE Account Property Buy: Why Tax Notices Hit NRIs?
💰 Tax & Budget
40d ago
💰
₹79 lakh

NRI's property buy flagged as unexplained cash — then fully cleared by tax tribunal

NRE Account Property Buy: Why Tax Notices Hit NRIs?

🤯 NRE account money is fully tax-free in India — yet the tax dept still sends notices if...

Read Full Story
📋 TL;DR

An NRI bought property worth ₹79 lakh using his NRE account, filed no Indian ITR, and got a tax notice for unexplained cash. The income tax appellate tribunal ruled fully in his favour. Here's why NRIs face this risk — and how to avoid it.

📰 What Happened

An NRI purchased property worth ₹79 lakh using funds held in his NRE account and did not file an Indian income tax return, as his Indian income was below the taxable threshold.

The Income Tax Department issued a notice treating the property purchase amount as 'unexplained cash credit', a serious addition under Section 68 of the Income Tax Act.

ITAT Ahmedabad ruled entirely in the NRI's favour, holding that NRE account funds represent foreign earnings already remitted to India and are fully exempt from Indian income tax.

🎯 What You Should Do

Keep all NRE account statements, foreign remittance receipts, and bank-to-bank transfer proofs for a minimum of 7 years — these are your primary defence against any tax notice on property purchases.

💡

File a 'nil' ITR in India if you make any high-value purchase (above ₹30 lakh) from your NRE or NRO account — it creates a paper trail and signals compliance to the tax department.

Check whether your property registrar has reported your transaction under the Annual Information Statement (AIS); log in at incometax.gov.in to verify what data the tax department already holds against your PAN.

💡 Pro Tip

Pro tip: NRE account interest is tax-free only while you remain an NRI — the moment you return to India permanently and your residential status changes, existing NRE balances become taxable. Convert to RFC accounts before you repatriate.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
SGB 2019-20 Series III: Your ₹1L is Now ₹4.44L
📊 Investing
40d ago
📉
344% absolute gain

Your ₹1 lakh SGB bet from 2019 is now worth ₹4.44 lakh today

SGB 2019-20 Series III: Your ₹1L is Now ₹4.44L

🤯 That 344% gain beats a decade of FD returns in just 7 years — roughly ₹3.44 lakh extra...

Read Full Story
📋 TL;DR

RBI has fixed the redemption price for Sovereign Gold Bond 2019-20 Series III at ₹15,310 per unit. Investors who bought at ₹3,449 have earned a 344% absolute return — and the interest income is completely tax-free.

📰 What Happened

RBI fixed the premature redemption price for SGB 2019-20 Series III at ₹15,310 per unit, with the redemption window opening August 14, 2026.

The bonds were originally issued at ₹3,449 per unit in 2019, meaning investors have earned an absolute return of approximately 344% on their investment.

A ₹1 lakh investment at the issue price — roughly 29 units — is now worth approximately ₹4.44 lakh at the RBI-fixed redemption price.

🎯 What You Should Do

Check your demat account or RBI Retail Direct portal right now to confirm if you hold SGB 2019-20 Series III units and how many.

💡

Compare your redemption options: premature exit at today's ₹15,310 price vs. holding to full 8-year maturity — both routes are capital-gains tax-free.

If you don't hold SGBs yet, track RBI's next SGB issuance calendar and apply early — new series are released in tranches throughout the year.

💡 Pro Tip

Premature SGB redemption after the 5-year lock-in is fully exempt from capital gains tax — the same benefit as holding to maturity. Most investors don't know this.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
Fake ₹6,000 Tax Notice? You Could Be Scammed
💰 Tax & Budget
40d ago
💰
₹6,000 fake tax demand

Scammers are sending fake IT notices to steal your money and data

Fake ₹6,000 Tax Notice? You Could Be Scammed

🤯 That ₹6,000 demand is roughly 60 cups of chai — and scammers count on panic making you...

Read Full Story
📋 TL;DR

A fake Income Tax notice demanding ₹6,000 is circulating online. The government's PIB Fact Check unit has confirmed it is a phishing scam. The real IT Department never asks for payments or sensitive details over email or unknown messages.

📰 What Happened

A fake Income Tax notice demanding a ₹6,000 payment is circulating through emails and messages across India.

The Press Information Bureau's Fact Check unit has officially confirmed the notice is a phishing scam with no government backing.

The Income Tax Department has a standing policy: it never solicits payments or sensitive financial information via email or unknown links.

🎯 What You Should Do

Log in directly to incometax.gov.in and check your e-filing dashboard — any genuine demand notice will appear there under 'Pending Actions'.

💡

Verify the Document Identification Number (DIN) on any notice you receive using the 'Verify Your Notice' tool on the official IT portal before paying anything.

Report suspicious tax-related messages to the IT Department's official phishing complaint email (phishing@incometaxindia.gov.in) and to PIB Fact Check via factcheck.pib.gov.in.

💡 Pro Tip

Pro tip: Every genuine Income Tax notice carries a unique DIN. No DIN on the notice — or a DIN that fails verification on the IT portal — means it is fake, period.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
SGB Premature Exit: 344% Gain — What You Decide
📊 Investing
40d ago
📉
344% gain in 5 years

Your SGB investment could have tripled — here's what to do now

SGB Premature Exit: 344% Gain — What You Decide

🤯 ₹10,000 invested in this SGB series is now worth ₹44,400 — more than most Indians save...

Read Full Story
📋 TL;DR

Sovereign Gold Bond holders from 2019-20 Series III can exit early and pocket up to 344% returns at ₹15,310 per unit. But should you cash out or hold till maturity? Here's what every SGB investor needs to know before deciding.

📰 What Happened

SGB 2019-20 Series III investors can redeem early on August 14, 2026, at ₹15,310 per unit set by RBI based on average gold prices.

The issue price in 2019 was around ₹3,443 per gram, making today's premature redemption price a gain of approximately 344% on the principal.

Premature redemption windows open from the 5th year and occur only on scheduled coupon payment dates — missing one means waiting for the next.

🎯 What You Should Do

Check your SGB series and issue date via your demat account or bank portal — confirm if you hold 2019-20 Series III before this window closes.

💡

Compare your personal need: if you don't need cash urgently, consider holding to the full 8-year maturity as capital gains remain tax-free either way.

If you decide to redeem, submit your request through the bank or broker where you hold the SGB at least 1–2 working days before the redemption date.

💡 Pro Tip

Capital gains from SGB redemption — both premature and at maturity — are fully tax-free for individual investors, unlike gold ETFs or physical gold where LTCG tax applies.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
EPFO Pension Live Q&A: 5 Things to Ask First
📋 Financial Planning
40d ago
💰
6 crore+ EPS members

Most don't know their exact pension entitlement until it's too late

EPFO Pension Live Q&A: 5 Things to Ask First

🤯 EPS pension can be as low as ₹1,000/month — less than a week of chai and snacks for...

Read Full Story
📋 TL;DR

EPFO is holding a live session to answer pension-related questions from EPS members. If you have doubts about your pension amount, eligibility, or withdrawal rights, this is a rare chance to get official clarity for free.

📰 What Happened

EPFO is conducting a live interactive session specifically to address Employee Pension Scheme (EPS) queries and grievances from its members.

Members can join via EPFO's official social media handles and ask questions in real time about pension eligibility, amounts, withdrawals, and transfers.

Key topics expected to be covered include EPS eligibility rules, higher pension applications, joint options, and how to calculate your monthly pension entitlement.

🎯 What You Should Do

Follow EPFO's official handles on YouTube and Twitter/X now and set a reminder for the session so you don't miss the live window.

💡

Write down your specific pension doubt in advance — mention your years of service, whether you've switched employers, and your current age — so you can ask a precise question.

Log into the EPFO member portal (member.epfindia.gov.in) before the session and note your UAN, service history, and any pending transfer or higher pension application status.

💡 Pro Tip

If you have worked for 9.5 years in EPS-covered jobs, EPFO rounds it up to 10 years — making you eligible for a monthly pension instead of a lump-sum withdrawal. Many members don't know this and exit early.

AI finds your cheapest loan from 100+ lenders

Check Your PF Balance
💰

Compare EMI Across 100+ Lenders

Same loan, different EMI. Find which lender saves you the most

Compare Now
WPI Hits 9.78%: What Your Wallet Pays Next
🌍 Economy & Inflation
40d ago
📉
9.78% WPI

Wholesale prices are rising fast — your grocery and EMI bills could follow

WPI Hits 9.78%: What Your Wallet Pays Next

🤯 A 9.78% WPI rise means the ₹200 you spend on veggies weekly could quietly become ₹220...

Read Full Story
📋 TL;DR

India's wholesale inflation jumped to 9.78% in July. When prices rise at the factory level, everyday goods get costlier soon after — and it could push the RBI to hold interest rates higher for longer, keeping your home and personal loan EMIs elevated.

📰 What Happened

India's Wholesale Price Index (WPI) inflation rose to 9.78% in July, signalling broad-based price pressure at the producer level across food, fuel, and manufactured goods.

Equity markets reacted negatively, with the Sensex falling around 300 points and Nifty 50 slipping below 24,350 as investors priced in the risk of prolonged higher interest rates.

Midcap and smallcap indices also declined nearly half a percent, reflecting wider market anxiety about inflation staying sticky and squeezing corporate profit margins.

🎯 What You Should Do

Lock in fixed deposit rates now for 1–3 year tenures — if inflation stays high, the RBI is unlikely to cut rates aggressively, so current FD rates near 7–7.5% are worth securing before any rate shift.

💡

Review your monthly household budget for categories most exposed to wholesale price rises — edible oils, packaged foods, and fuel — and identify where you can substitute or reduce consumption to protect savings.

If you have a floating rate home loan, check your loan statement for the next reset date and calculate your new EMI — a prolonged high-rate environment means no relief is likely before early 2026.

💡 Pro Tip

WPI typically leads CPI by 6–8 weeks. If WPI is at 9.78% today, expect your local market prices to reflect this surge by September–October — plan grocery and household budgets now, not later.

AI finds your cheapest loan from 100+ lenders

Compare FD Rates Now
NRI Investing in India: 5 Rules You Must Know
📊 Investing
40d ago
💰
₹0 tax on NRE returns

Your NRE account interest and gains are fully tax-free in India

NRI Investing in India: 5 Rules You Must Know

🤯 An NRI can invest in Indian mutual funds from abroad — but one wrong account type...

Read Full Story
📋 TL;DR

NRIs can legally invest in Indian stocks and mutual funds using NRE or NRO accounts, but the rules on repatriation, taxation, and account types are different from resident Indians. Here's what you need to know before investing.

📰 What Happened

NRIs can invest in Indian stocks and mutual funds using NRE or NRO accounts, subject to RBI's Portfolio Investment Scheme (PIS) guidelines.

An NRE account offers full repatriability and zero Indian tax on interest and qualifying returns, making it the most tax-efficient route for NRI investors.

US and Canada-based NRIs face additional restrictions — most Indian mutual fund houses do not accept their investments due to FATCA compliance requirements.

🎯 What You Should Do

Open an NRE savings account with an RBI-authorised bank and apply for PIS permission before attempting to invest in Indian equities.

💡

Check whether your chosen mutual fund house accepts applications from your country of residence — especially critical if you live in the US or Canada.

Consult a cross-border tax professional to understand your LTCG liability in India and whether a tax treaty between India and your resident country reduces your effective rate.

💡 Pro Tip

Pro tip: NRIs can invest in direct mutual fund plans online via platforms that support NRE account linking — this saves 0.5–1% annually in distributor commissions compared to regular plans.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
EPF Account Frozen? ₹40,000 May Be Stuck
📋 Financial Planning⚠️BORROWER ALERT
40d ago
💰
21.55 lakh accounts

Your EPF money could be sitting frozen, earning nothing for years

EPF Account Frozen? ₹40,000 May Be Stuck

🤯 ₹40,000 average stuck balance = 444 cups of chai at ₹90 each — just sitting idle

Read Full Story
📋 TL;DR

Over 21 lakh EPF accounts are inoperative with an average balance of ₹40,000 each. If you changed jobs and never transferred or claimed your PF, your money could be stuck. Here's how to check and fix it fast.

📰 What Happened

Over 21.55 lakh EPF accounts are currently inoperative — up 84% in four years — with a combined dormant balance that has more than doubled in the same period.

The average inoperative EPF account holds around ₹40,000, typically belonging to workers who changed jobs and never transferred or claimed their old provident fund balance.

EPFO is now actively identifying dormant accounts and pushing members to revive them, with the government taking steps to reunite account holders with their forgotten PF money.

🎯 What You Should Do

Log in to the EPFO Member Portal (member.epfindia.gov.in) with your UAN and check if you have any old or inoperative PF accounts linked to previous employers.

💡

Transfer your old EPF balance to your current employer's PF account online using Form 13 — the entire process can be done without visiting any EPFO office if your UAN is KYC-verified.

If you are between jobs or self-employed, file a final PF settlement claim using Form 19 after a gap of at least two months from your last date of employment to withdraw the full balance.

💡 Pro Tip

Interest earned in an inoperative EPF account is still credited annually, but it becomes fully taxable — unlike active PF interest which is tax-free up to ₹2.5 lakh contribution per year. Transfer fast to avoid a surprise tax bill.

AI finds your cheapest loan from 100+ lenders

Check Your EPF Balance
Move PPF to Bank: 3 Steps, Zero Interest Loss
🏦 Savings & Deposits
40d ago
💰
₹100 + GST

This small fee lets you move your PPF or SSA to a bank branch near you

Move PPF to Bank: 3 Steps, Zero Interest Loss

🤯 That ₹100 transfer fee is less than two cups of café coffee — and it buys you...

Read Full Story
📋 TL;DR

You can shift your PPF, Sukanya Samriddhi, or SCSS account from a Post Office to a bank without losing interest or continuity. The process costs just ₹100 plus GST and requires a few documents. Here's how to do it right.

📰 What Happened

PPF, Sukanya Samriddhi (SSA), and SCSS account holders can officially transfer their accounts from Post Offices to scheduled commercial banks by submitting a transfer request at the originating Post Office.

The transfer fee is ₹100 plus applicable GST — a one-time charge; account continuity, original open date, lock-in period, and interest accrual are all fully preserved after the move.

Required documents typically include the original passbook, a KYC set (Aadhaar, PAN), a transfer request form available at the Post Office, and destination bank account details for credit linkage.

🎯 What You Should Do

Visit your nearest Post Office with your original passbook and KYC documents — submit the transfer request form there (not at the bank) to initiate the move.

💡

Confirm with the destination bank branch beforehand that it is authorised to hold PPF, SSA, or SCSS accounts — not every branch of every bank accepts all three schemes.

After transfer is complete, update your new passbook details on the Income Tax portal (for PPF 80C claims) and link the bank account for SCSS interest credit to avoid payment disruptions.

💡 Pro Tip

Pro tip: Transfer your SSA account before your daughter turns 10 — after that, certain operational rules tighten and branch-level processing can get more complex.

FD vs loan EMI — which earns you more? AI will tell

Compare Now
RBI Loan Pricing Shake-Up: Is Your EMI Fair?
🏛️ RBI Policy📢POLICY UPDATE
40d ago
💰
₹52,000 extra

Hidden bank spreads could be costing your home loan this much every year

RBI Loan Pricing Shake-Up: Is Your EMI Fair?

🤯 The spread your bank adds to your loan rate is rarely disclosed — like a restaurant...

Read Full Story
📋 TL;DR

RBI is working on new rules to make loan pricing clearer for borrowers. Banks may soon be required to explain exactly how they set your interest rate — especially for floating rate and small-ticket loans — potentially by April 2027.

📰 What Happened

RBI has floated a proposal to increase transparency in how banks price loans, particularly floating rate products where the spread over the benchmark is rarely disclosed to borrowers.

The new framework, if finalised, could require lenders to clearly state and justify the spread component of loan interest rates, covering home loans, personal loans, and small-ticket credit.

Implementation is being discussed for around April 2027, giving banks a transition window but signalling that opaque loan pricing practices are firmly in the regulator's crosshairs.

🎯 What You Should Do

Request your bank's loan pricing sheet — ask them to break down your interest rate into the benchmark component and the spread in writing, so you can track if future RBI cuts are fully passed on.

💡

Compare your effective loan rate against the current repo rate (6.25% as of mid-2025) — if your floating home loan is above 9.5%, demand a written explanation of the spread your bank is charging.

If you have a small personal loan charging above 24% annually, check whether it was disbursed with a clear cost-of-credit disclosure — you may have grounds to request a reset or switch lenders.

💡 Pro Tip

Under RBI's existing External Benchmark Lending Rate rules, banks must reset your floating loan rate at least once every three months — if yours hasn't moved after two consecutive RBI rate cuts, file a written grievance with your bank's nodal officer before escalating to RBI's Integrated Ombudsman.

RBI rules change your EMI — check your current rate

Compare Rates
📊

Free CIBIL Score Check

Check your credit score instantly — zero impact on CIBIL

Check Score Free
Builder Delaying Flat? RERA Gives You 6% Back
📋 Financial Planning
40d ago
📉
6% annual interest

Your builder owes you this penalty for every month your flat is delayed

Builder Delaying Flat? RERA Gives You 6% Back

🤯 6% interest on a ₹60L flat = ₹3,600/month — enough to cover your rent while you wait

Read Full Story
📋 TL;DR

If your builder is delaying your flat without explanation, you have real legal rights under RERA and Consumer Protection laws. You can claim interest compensation, file complaints, and even demand a refund — without hiring an expensive lawyer first.

📰 What Happened

RERA (Real Estate Regulation and Development Act, 2016) legally binds builders to deliver possession by the date in the registered sale agreement or pay monthly interest compensation to buyers.

Homebuyers can file complaints on their state RERA portal independently — without a lawyer — and adjudicating officers can award interest, order possession, or grant a full refund plus compensation.

The Consumer Protection Act 2019 provides a parallel legal route: buyers can approach District, State, or National Consumer Commissions for deficiency in service, mis-selling, or false advertising by builders.

🎯 What You Should Do

Dig out your registered sale agreement and note the exact promised possession date — this date is your legal starting point for calculating interest owed under RERA.

💡

File a complaint on your state's official RERA portal (e.g., MahaRERA, RERA Karnataka) using the project's RERA registration number, which must be printed on all builder communications.

Send a formal written notice to your builder via registered post before approaching consumer court — courts look more favourably at buyers who have documented their attempts to resolve the matter.

💡 Pro Tip

If your builder's project is NOT RERA-registered (illegal for projects over 500 sq m or 8 units post-2016), you can directly approach the consumer court AND report the builder to the state RERA authority — non-registration itself is a punishable offence with fines up to 10% of project cost.

AI finds your cheapest loan from 100+ lenders

Know Your Legal Rights
Travel Forex: 5 Currencies That Cost Indians Most
📋 Financial Planning
40d ago
💰
₹7,000+ saved

Smart currency choice can save you this much on a ₹1 lakh travel budget

Travel Forex: 5 Currencies That Cost Indians Most

🤯 Buying forex at the airport can cost ₹200–₹400 more per $100 than your bank branch —...

Read Full Story
📋 TL;DR

Indian travellers are buying more Thai baht, UAE dirhams, and Singapore dollars than ever. But where and how you buy foreign currency matters as much as which currency you pick — hidden margins can quietly eat 3–5% of your travel budget.

📰 What Happened

Indian outbound travel has surged, and forex demand for Thai baht, UAE dirham, and Singapore dollar has grown sharply — reflecting popular holiday and business corridors beyond the US.

Currency conversion margins vary widely — airport kiosks, bank branches, authorised money changers, and forex cards all offer different effective rates on the same currency.

TCS at 20% now applies on overseas forex spends above ₹7 lakh per person per year under LRS, making large travel budgets more expensive upfront unless planned carefully.

🎯 What You Should Do

Compare the exact rupee-per-unit rate (not just the 'zero commission' claim) across your bank, an FFMC-authorised money changer, and a forex card before buying any foreign currency.

💡

Load a multi-currency forex card at least 48–72 hours before departure through your bank or an RBI-authorised full-fledged money changer to lock in a better rate and avoid airport markups.

Track your total overseas forex spend across the financial year — if you are approaching ₹7 lakh, plan purchases to manage TCS cash flow and ensure you claim it back when filing your ITR.

💡 Pro Tip

Pro tip: Carrying 70–80% of your travel money on a forex card and keeping 20% in cash gives you the best of both worlds — better rates on the bulk, and cash for small vendors who don't accept cards.

AI finds your cheapest loan from 100+ lenders

Compare Forex Card Rates
Hot IPO, 25X Subscribed: Will You Get Allotment?
📊 Investing
40d ago
🎯
25.8X oversubscribed

Your IPO allotment odds are razor-thin when demand runs this hot

Hot IPO, 25X Subscribed: Will You Get Allotment?

🤯 At 25.8X subscription, statistically only 1 in 26 retail applicants gets shares —...

Read Full Story
📋 TL;DR

When an IPO gets subscribed over 25 times, most retail applicants receive nothing. Understanding how SEBI's lottery allotment works — and using family PAN accounts legally — can meaningfully improve your odds.

📰 What Happened

A major ecommerce logistics IPO was subscribed over 25 times on its final day, meaning bids far exceeded the shares actually available for allotment.

The non-institutional investor (NII) category saw the highest demand at over 50 times subscription, reflecting strong appetite from high-net-worth applicants.

Retail individual investors (RIIs) compete in a separate lottery-based allotment pool where SEBI rules cap each applicant at one lot regardless of bid size.

🎯 What You Should Do

Apply for exactly one lot per eligible PAN in your family — spouse, parents — to multiply independent lottery chances without violating SEBI rules.

💡

Check your ASBA-linked bank account has sufficient cleared balance before the IPO closes, as blocked funds attract no extra interest during the lock-in period.

Compare the IPO's Grey Market Premium (GMP) trend on listing day before deciding to hold or sell — a fading GMP often signals weak post-listing momentum.

💡 Pro Tip

Pro tip: SEBI's retail allotment is pure lottery — applying for the maximum lots under one PAN wastes no money but gains zero extra probability. One lot per PAN is always the optimal strategy.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
Sending Money Abroad? 5 Hidden Fees Cut Your Transfer
📋 Financial Planning
40d ago
💰
₹3,500+ lost

Your ₹50,000 foreign remittance silently shrinks by this much in hidden fees

Sending Money Abroad? 5 Hidden Fees Cut Your Transfer

🤯 Sending ₹50,000 abroad can cost more in hidden FX mark-ups than 60 cups of chai — and...

Read Full Story
📋 TL;DR

Every time you send or receive money internationally, banks and transfer services quietly eat into your amount through exchange rate mark-ups, flat fees, and correspondent bank charges. Here's what to watch and how to lose less.

📰 What Happened

International money transfers carry multiple hidden cost layers — sender bank fees, FX rate mark-ups, and correspondent bank charges — that together can erode 3–7% of your transfer value.

RBI's Liberalised Remittance Scheme permits Indian residents to remit up to USD 2,50,000 per financial year abroad, but Tax Collected at Source (TCS) at 5% now applies on outward remittances exceeding ₹7 lakh annually.

RBI-authorised fintech remittance platforms typically offer exchange rates significantly closer to the mid-market rate than traditional bank wire transfers, reducing the total cost of sending money internationally.

🎯 What You Should Do

Compare the 'recipient gets' amount — not the advertised fee — across your bank and at least one RBI-authorised remittance platform before every transfer.

💡

Track your total outward remittances each financial year; if you cross ₹7 lakh, factor in the 5% TCS outflow and claim it back when you file your ITR to recover the cash.

Ask your bank explicitly for the exchange rate spread over the mid-market rate — if they cannot answer or quote more than 2% above Google's rate, switch to a licensed money transfer operator for that transaction.

💡 Pro Tip

Pro tip: Timing your transfer on a weekday morning (IST) when both Indian and destination-country forex markets are active simultaneously often gets you a tighter exchange rate spread than weekend or late-night transfers.

AI finds your cheapest loan from 100+ lenders

Compare Transfer Rates Now
Divorce Maintenance Cut: What Courts Check in Your Income?
📋 Financial Planning
40d ago
💰
₹25,000/month

Courts can revise your maintenance order — even years after it was set

Divorce Maintenance Cut: What Courts Check in Your Income?

🤯 ₹25,000/month maintenance = roughly 5% of a ₹63L annual salary — less than many car EMIs.

Read Full Story
📋 TL;DR

Courts don't just look at your salary slip when deciding maintenance. A Delhi HC ruling shows judges weigh both spouses' real earning capacity, lifestyle, and fairness — and can revise orders retroactively, sometimes years later.

📰 What Happened

Delhi HC reduced interim maintenance from ₹30,000 to ₹25,000/month for a spouse in a matrimonial dispute, despite the husband earning ₹63 lakh annually.

The court applied a balanced approach, weighing both the husband's income and the wife's own earning capacity and lifestyle needs.

The revised maintenance order was applied retroactively from April 2021, showing courts can rewrite financial obligations from a past date.

🎯 What You Should Do

Document all income sources honestly — courts increasingly scrutinize bank statements, ITRs, Form 16, and business cash flows, not just salary slips.

💡

If you are receiving maintenance, keep records of your own employability status — gap in career, qualifications, and job market access all influence the court's calculation.

Consult a family law attorney before any interim maintenance order becomes final — retroactive revisions can create sudden large lump-sum liabilities or recoveries.

💡 Pro Tip

Pro tip: Courts can impute income to a spouse who is deliberately underemployed or unemployed by choice — staying home voluntarily does not guarantee higher maintenance.

AI finds your cheapest loan from 100+ lenders

Plan Your Finances Now
🎯

AI Loan Agent — 100+ Lenders

AI scans all lenders and finds your cheapest EMI automatically

Find Cheapest Loan
₹5L Health Cover: Is Your Family Underinsured?
🛡️ Insurance
40d ago
💰
₹25–40 lakh

Your family may need this much health cover to avoid out-of-pocket ruin today

₹5L Health Cover: Is Your Family Underinsured?

🤯 A 3-day ICU stay in a Delhi private hospital can cost more than 8 months of a ₹50,000...

Read Full Story
📋 TL;DR

Health insurance of ₹5–10 lakh that felt safe five years ago may now cover only a fraction of a serious illness bill. Rising hospital costs, new treatments, and metro pricing mean most Indian families need to rethink their coverage — fast.

📰 What Happened

Medical inflation in India runs at 10–14% annually, making a ₹5–10 lakh health cover bought before 2020 worth significantly less in real hospital purchasing power today.

Major private hospitals in metro cities now charge ₹4–7 lakh for cardiac procedures and ₹20–30 lakh or more for cancer treatment, organ transplants, and complex surgeries.

Insurers and financial planners now recommend a minimum effective cover of ₹25–40 lakh per family in tier-1 cities, and ₹15–20 lakh even in tier-2 towns.

🎯 What You Should Do

Calculate your real coverage gap: add up your base policy sum insured plus any employer group cover, then check whether it would cover a 7-day ICU stay at the nearest major private hospital.

💡

Buy a super top-up plan to bridge the gap cheaply — a ₹20 lakh top-up with a ₹5 lakh deductible costs a fraction of a fresh standalone policy and plugs the most dangerous shortfall.

At your next renewal, activate the restoration or recharge benefit if your insurer offers it — this refills your cover mid-year if one claim exhausts the sum insured, protecting you from a second hospitalisation in the same policy year.

💡 Pro Tip

Super top-up premiums are eligible for the ₹25,000 Section 80D tax deduction (₹50,000 for senior citizens) — most people claim only their base policy and leave this tax saving unused.

Insurance + loans sorted — one app for your money

Get GoCredit
Beyond FDs: Does Your ₹50L Need a Wealth Plan?
📋 Financial Planning
40d ago
💰
₹1 crore+

The wealth level where most Indians finally need a real financial plan

Beyond FDs: Does Your ₹50L Need a Wealth Plan?

🤯 Most Indians spend more time planning a ₹50,000 vacation than planning what to do with...

Read Full Story
📋 TL;DR

Having money is not the same as managing it well. Once your savings cross a certain level, random FDs and SIPs are not enough — you need a proper wealth plan covering family goals, asset allocation, and tax efficiency.

📰 What Happened

Wealth management in India is evolving beyond just picking stocks or mutual funds — it now includes family goal-setting, succession planning, and asset allocation strategy.

Most middle-class Indians accumulate financial products (FDs, SIPs, real estate, insurance) without a unified plan that connects these to actual life goals or family needs.

Global economic shifts — including US Federal Reserve rate changes and rupee depreciation — increasingly affect Indian household portfolios, especially those with international fund exposure or foreign education goals.

🎯 What You Should Do

List every financial product you own (FD, SIP, LIC, real estate, PF) and map each one to a specific life goal — if you can't, that product needs review.

💡

Check your asset allocation ratio today: if more than 60% of your savings are in one asset class (real estate, FDs, or equity alone), you are taking more risk than you realise — rebalance.

Draft a basic will or at least update nominees across all bank accounts, demat accounts, and insurance policies — a nominee only transfers custody, not legal ownership, without a will.

💡 Pro Tip

Pro tip: Rebalancing once a year — moving gains from equity back into debt when markets are up — is free, takes 30 minutes, and historically reduces portfolio volatility by 15-20% without sacrificing returns.

AI finds your cheapest loan from 100+ lenders

Review Your Financial Plan
Hidden Foreign Account? Black Money Act Costs You 30%
💰 Tax & Budget
40d ago
💰
₹0 exemption

Your undisclosed foreign assets get zero basic exemption under Black Money Act

Hidden Foreign Account? Black Money Act Costs You 30%

🤯 Even a dormant Dubai account with ₹500 can trigger a tax demand bigger than 10 years...

Read Full Story
📋 TL;DR

If you hold an undisclosed foreign bank account or overseas shares and haven't declared them to Indian tax authorities, the Black Money Act 2015 can hit you with a flat 30% tax plus 90% penalty — no exemptions, no deductions, no mercy.

📰 What Happened

India's Income Tax Appellate Tribunal upheld a tax demand on a taxpayer who held an undisclosed Dubai bank account and UAE shares not declared in Indian tax returns.

Under Section 3 of the Black Money Act 2015, tax is levied in the year the Assessing Officer discovers the foreign asset — not the year it was created or earned income.

The Black Money Act imposes a flat 30% tax on the total value of undisclosed foreign assets with no basic exemption, deduction, or treaty benefit available to the taxpayer.

🎯 What You Should Do

Check your ITR's Schedule FA (Foreign Assets) section and declare every overseas bank account, property, or shareholding you hold or held as an Indian tax resident.

💡

If you returned to India from abroad and have old NRI accounts, close them formally or convert them to RFC/NRO accounts and disclose in your current year's ITR immediately.

Consult a tax professional about the one-time disclosure route if you have undisclosed foreign assets — voluntary disclosure before detection dramatically reduces penalty exposure.

💡 Pro Tip

Pro tip: Even a zero-balance or closed foreign account must be reported in Schedule FA if it existed during the financial year — 'nil balance' is not a valid reason to skip disclosure.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
NRI or Resident? NSC's ₹1.5L Tax Rule Explained
🏦 Savings & Deposits
40d ago
📉
7.7% guaranteed

NSC offers this return — but only if you qualify as a resident Indian

NRI or Resident? NSC's ₹1.5L Tax Rule Explained

🤯 NSC's 7.7% beats most bank FDs — but your passport status decides if you can even open...

Read Full Story
📋 TL;DR

NSC is a government-backed savings scheme paying 7.7% interest with Section 80C tax benefits up to ₹1.5 lakh. But it is strictly for resident Indians — NRIs cannot invest in NSC. If you moved abroad after opening one, read this carefully.

📰 What Happened

NSC is a government-backed small savings scheme offering 7.7% annual interest, with a 5-year lock-in period and Section 80C deduction eligibility up to ₹1.5 lakh per year.

The scheme is legally restricted to resident Indian citizens only — Non-Resident Indians (NRIs), Overseas Citizens of India (OCI), and Persons of Indian Origin (PIO) cannot open new NSC accounts.

An existing NSC account opened before a person became an NRI can typically be held to maturity, but no fresh investment or reinvestment is permitted once the holder becomes non-resident.

🎯 What You Should Do

Check your FEMA residential status before investing in any post office small savings scheme — NRI status disqualifies you from NSC, PPF top-ups, and several other schemes.

💡

If you are an NRI seeking tax-free, government-backed returns, compare NRE fixed deposits (interest exempt from Indian tax) and FCNR deposits as eligible alternatives.

If you hold an existing NSC that was opened as a resident, inform your post office of your NRI status and clarify maturity redemption rules to avoid legal complications at payout.

💡 Pro Tip

Interest earned on NSC is deemed reinvested each year and qualifies for Section 80C deduction for resident investors — but only the final year's interest is actually paid out as cash, so plan your 80C claims across all 5 years.

FD vs loan EMI — which earns you more? AI will tell

Compare Now
Mumbai Property Up 8% in 9 Months: Is Now Your Time?
📈 Market Trends
40d ago
💰
₹33,100 → ₹35,900/sq ft

Mumbai's Juhu saw this price jump in just 9 months — your real estate timing matters

Mumbai Property Up 8% in 9 Months: Is Now Your Time?

🤯 That 8% jump in Juhu equals roughly 18 months of chai budget for an average Mumbai...

Read Full Story
📋 TL;DR

Prime Mumbai localities like Juhu saw property prices jump nearly 8% in under a year. If you are planning to buy or invest in Mumbai real estate, here is what this trend means for your budget, loan, and timing.

📰 What Happened

Property rates in select Mumbai micro-markets rose from around ₹33,100 per sq ft to ₹35,900 per sq ft between September 2025 and June 2026 — a jump of nearly 8.5% in nine months.

Juhu remains one of Mumbai's priciest localities with average asking prices around ₹45,000 per sq ft, driven by limited supply, proximity to the sea, and strong rental demand.

High-profile lease deals in premium Mumbai neighbourhoods signal continued investor and end-user confidence in top-tier urban real estate even as affordability tightens for middle-class buyers.

🎯 What You Should Do

Calculate your revised home loan eligibility today using current property prices — a ₹3–5L price rise can reduce your eligible loan amount significantly at the same income level.

💡

Compare home loan interest rates across at least 3 lenders before applying — a 0.25% rate difference on a ₹60L loan saves over ₹1.5L in total interest over 20 years.

Check your CIBIL score now and aim for 750+ before applying — a good score can unlock the lowest slab rates, partially offsetting the impact of rising property prices on your EMI.

💡 Pro Tip

Pro tip: Ask your lender for a repo-rate-linked floating loan — when RBI cuts rates, your EMI drops automatically without requiring a separate request or refinancing paperwork.

AI finds your cheapest loan from 100+ lenders

Check Your Loan Offers
🛡️

Recovery Harassment? Get Help

Loan Kavach: legal team fights harassment calls for you

Get Protection
Ladki Bahin ₹3,000 Payout: Is Your Account Ready?
📋 Financial Planning
40d ago
💰
₹3,000

Your Ladki Bahin payment could arrive doubled before Raksha Bandhan

Ladki Bahin ₹3,000 Payout: Is Your Account Ready?

🤯 ₹3,000 covers roughly 60 cups of chai — or a full month's vegetable budget for many...

Read Full Story
📋 TL;DR

Maharashtra's Ladki Bahin Yojana may pay a combined ₹3,000 instalment (July + August) before Raksha Bandhan. But no official date is confirmed yet. Here's what enrolled women should check right now so the money actually lands in their account.

📰 What Happened

Maharashtra's Ladki Bahin Yojana gives ₹1,500 per month to eligible women, but July and August instalments remain unconfirmed and unpaid as of now.

The state government is reported to be considering releasing a combined ₹3,000 payment before Raksha Bandhan, though no official date or circular has been issued.

Beneficiaries must have an Aadhaar-linked, active bank account to receive the direct benefit transfer — any mismatch causes silent payment failure.

🎯 What You Should Do

Log into the Nari Shakti Doot app or the Maharashtra government's official Ladki Bahin portal to check your current application and payment status.

💡

Visit your bank branch or use net banking to confirm your Aadhaar number is seeded to your account — call 14545 (UIDAI helpline) if unsure.

If your name spelling differs between Aadhaar and your bank passbook, submit a correction request at either the bank or Aadhaar centre before the payment window opens.

💡 Pro Tip

Pro tip: Even if your payment shows 'approved', a dormant bank account (no transaction in 12+ months) will reject the DBT credit — make one small transaction now to reactivate it.

AI finds your cheapest loan from 100+ lenders

Check Your Benefit Status
Health Insurance Too Costly? 5 Reforms Your Policy Needs
🛡️ Insurance
40d ago
💰
₹5 lakh

Average Indian family spends this on a single hospitalisation without insurance

Health Insurance Too Costly? 5 Reforms Your Policy Needs

🤯 One ICU night in a metro hospital costs more than 3 months of EMI on a ₹30L home loan.

Read Full Story
📋 TL;DR

Cheaper premiums alone won't fix health insurance in India. The real problem is that hospital charges are unregulated, so even insured families end up paying huge bills. Here's what needs to change — and what you can do right now.

📰 What Happened

Health insurance premiums have risen sharply in India, but experts argue the root cause is unregulated hospital charges — not insurer inefficiency alone.

Private hospitals charge significantly more than government hospitals for identical procedures, with no binding price cap on tertiary or super-speciality care.

Industry voices are calling for standardised treatment costs across hospital categories so that claims and premiums can be managed within predictable limits.

🎯 What You Should Do

Check your policy's room rent sub-limit today — if it's below ₹3,000/day for a metro city, upgrade your plan before your next renewal to avoid proportional claim cuts.

💡

Compare at least 3 health insurance quotes on IRDAI's Bima Sugam portal or an IRDAI-registered aggregator before renewing, focusing on procedure-wise sub-limits and restoration benefits.

Ask your HR department if your group health cover includes a top-up option — topping up a corporate policy is far cheaper than buying a separate super-top-up plan independently.

💡 Pro Tip

Pro tip: A super top-up plan activates only after your base cover is exhausted — buying a ₹15 lakh super top-up above a ₹5 lakh base policy costs as little as ₹4,000–6,000/year for a 35-year-old.

Insurance + loans sorted — one app for your money

Get GoCredit
99X IPO Frenzy: How to Boost Your Allotment Odds
📊 Investing
40d ago
🎯
99X oversubscribed

Your IPO allotment odds just got brutally thin — here's what to do

99X IPO Frenzy: How to Boost Your Allotment Odds

🤯 At 99X oversubscription, your ₹15,000 IPO application competes with ₹14.85 lakh worth...

Read Full Story
📋 TL;DR

Shiprocket's IPO was oversubscribed 99 times, meaning most retail investors won't get shares. Here's how the allotment system works and what smart retail investors can do to improve their chances.

📰 What Happened

Shiprocket's IPO closed with 99.38X overall oversubscription, meaning investors bid for nearly 100 times the shares actually available for public allotment.

Qualified Institutional Buyers (QIBs) oversubscribed their reserved quota by 122.8X, reflecting intense institutional demand for the logistics-tech company's shares.

The Non-Institutional Investor (NII) category, which covers high-net-worth applicants bidding above ₹2 lakh, was oversubscribed 88.99X, leaving retail investors in a fierce lottery.

🎯 What You Should Do

Apply through every eligible family member's separate demat account (each with a unique PAN) — this is legal, SEBI-compliant, and your best shot at increasing allotment probability.

💡

Use the ASBA (Application Supported by Blocked Amount) facility through your bank's net banking or UPI for IPO applications — your funds stay in your account and earn interest until shares are allotted.

Check your IPO allotment status on the registrar's website (Link Intime or KFin Technologies) within 6 days of the issue closing — if unallotted, your refund should arrive automatically within 1 business day.

💡 Pro Tip

In oversubscribed retail categories, SEBI mandates a computerised lucky draw — applying at the cutoff price (not a specific price) ensures you're not accidentally excluded from allotment.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
NSC for NRIs: Can You Invest & Save Tax?
🏦 Savings & Deposits
40d ago
💰
₹1.5 lakh

Your Section 80C limit NSC offers — but only if you qualify as a resident

NSC for NRIs: Can You Invest & Save Tax?

🤯 NSC earns ~7.7% annually — more than most savings accounts but only resident Indians...

Read Full Story
📋 TL;DR

NSC is a popular Post Office savings scheme with guaranteed returns and tax benefits. But if you are an NRI, you cannot open a new NSC account. Existing NSC holders who later became NRIs can continue until maturity — but lose the Section 80C deduction.

📰 What Happened

NSC is a Post Office small savings scheme restricted to resident Indians — NRIs cannot open new NSC accounts under current rules.

Existing NSC accounts opened before a person became NRI can be held to maturity, but no fresh deposits or renewals are allowed.

Section 80C tax deductions on NSC investments are available only to resident taxpayers — NRIs cannot claim this benefit on Indian returns.

🎯 What You Should Do

Check your residential status under FEMA before assuming you can invest in NSC — even one year abroad can change your eligibility.

💡

If you hold a legacy NSC and are now an NRI, let it run to maturity and collect the proceeds into your NRO account without tax deduction at source.

Compare NRE Fixed Deposits (tax-free interest, fully repatriable) as your go-to guaranteed-return alternative to NSC while you are abroad.

💡 Pro Tip

NRE FD interest is completely exempt from Indian income tax and can be freely sent back abroad — NSC offers neither advantage for NRIs.

FD vs loan EMI — which earns you more? AI will tell

Compare Now
NRI KYC Relaxed: Invest in India in Fewer Steps?
📊 Investing🔴BREAKING NEWS
40d ago
💰
3 crore+ NRIs

NRI investors in India just got easier KYC rules for their money

NRI KYC Relaxed: Invest in India in Fewer Steps?

🤯 An NRI sending ₹83,000/month home spends more on bank paperwork than 3 months of chai.

Read Full Story
📋 TL;DR

SEBI has relaxed KYC rules for NRIs, OCIs, and foreign nationals investing in India. This means less paperwork, simpler document requirements, and easier access to Indian mutual funds and stock markets from abroad.

📰 What Happened

SEBI has officially relaxed KYC document norms for NRIs, OCIs, and foreign nationals investing in Indian securities markets.

The relaxation reduces documentation friction — overseas addresses, foreign passports, and OCI cards will now be accepted more flexibly during KYC verification.

This move aims to make Indian mutual funds, stocks, and demat accounts more accessible to the global Indian diaspora and foreign investors.

🎯 What You Should Do

Check with your broker or AMC if your NRI relative's investment folio is frozen due to KYC issues — it may now be resolvable under relaxed norms.

💡

Update your nominee details in mutual fund and demat accounts if your nominee is an NRI or OCI — their KYC verification just became simpler.

If you are an NRI planning to invest in India, contact a SEBI-registered intermediary to complete KYC under the new relaxed framework before markets move.

💡 Pro Tip

Pro tip: NRI folios frozen for KYC non-compliance can often be reactivated without fresh investment — just submit updated documents to your AMC's NRI desk.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
📈

Improve CIBIL by 100 Points

AI analyzes your report and gives a personalized action plan

Boost My Score
FIRE at 40: Can Your ₹6 Crore Fund Early Retirement?
📋 Financial Planning
40d ago
💰
₹6 crore

Your FIRE target could be this high — most Indians underestimate it badly

FIRE at 40: Can Your ₹6 Crore Fund Early Retirement?

🤯 Skipping 10 years of office chai breaks saves ₹1.8 lakh — but your SIP does the real...

Read Full Story
📋 TL;DR

Early retirement sounds dreamy, but reaching FIRE in India needs serious planning. You need roughly 25-30 times your annual expenses saved up — and that number is bigger than most people think.

📰 What Happened

A post by a FIRE community member claiming early retirement beats corporate drudgery went viral, sparking widespread debate about lifestyle, purpose, and financial independence in India.

Thousands of responses revealed a split: many Indians agree office commutes and pointless meetings drain life, but others worry that retiring early without enough corpus creates new financial anxiety.

Financial Independence Retire Early (FIRE) is gaining traction among Indian millennials, but most online discussions skip the hard math — specifically how much corpus is actually needed given Indian inflation and healthcare costs.

🎯 What You Should Do

Calculate your real FIRE number: multiply your current monthly expenses by 12, then by 25 — that is your minimum target corpus; if you spend ₹1 lakh/month, you need at least ₹3 crore.

💡

Stress-test your retirement plan against 6% annual inflation and 14% healthcare inflation using a free SIP calculator — most people discover their target is 30–40% higher than their first estimate.

Open or top up a dedicated retirement SIP in a diversified equity fund today — even ₹10,000/month started at age 30 can compound to over ₹1.5 crore by age 50 at historical returns.

💡 Pro Tip

Pro tip: In India, plan for a 50-year retirement if you exit at 40. Use the 3.3% withdrawal rate — not 4% — because Indian inflation erodes purchasing power faster than Western models assume.

AI finds your cheapest loan from 100+ lenders

Plan Your FIRE Number
India Post Life Insurance: Are You Now Eligible?
🛡️ Insurance
40d ago
💰
₹0 premium wasted

Rural life cover is now open to you — even if you live in a city

India Post Life Insurance: Are You Now Eligible?

🤯 A ₹500/month India Post life policy can cover ₹10L — less than your Netflix + Swiggy bill.

Read Full Story
📋 TL;DR

India Post has expanded Rural Postal Life Insurance eligibility to all savings account holders, dropping the rural-only requirement. If you have a Post Office savings account, you may now qualify for affordable government-backed life cover — wherever you live.

📰 What Happened

India Post has expanded Rural Postal Life Insurance (RPLI) eligibility to cover all Post Office savings account holders, removing the earlier rural-residence requirement.

The change means urban and semi-urban residents who hold a Post Office savings account can now apply for government-backed life insurance under the RPLI scheme.

RPLI is one of India's oldest and lowest-cost life insurance programmes, administered by India Post under the Department of Posts with IRDAI oversight.

🎯 What You Should Do

Check if you or a family member holds a Post Office savings account — that account is now your entry point to affordable RPLI life cover.

💡

Visit your nearest post office branch and ask for an RPLI eligibility check and premium quote based on your age and desired sum assured.

Compare RPLI premium rates against your existing term plan or LIC policy — if RPLI is cheaper for similar cover, consider supplementing your protection.

💡 Pro Tip

RPLI allows a loan against your policy after just 3 years of premium payments — useful as a low-interest emergency credit option most policyholders never use.

Insurance + loans sorted — one app for your money

Get GoCredit
SEBI Settlement Revamp: Your ₹10L Case Gets Fast-Track?
📈 Market Trends
40d ago
💰
₹10 lakh

Your SEBI case could now settle faster under a new fast-track route

SEBI Settlement Revamp: Your ₹10L Case Gets Fast-Track?

🤯 The 20% extra settlement charge SEBI wants to scrap could save you more than 6 months...

Read Full Story
📋 TL;DR

SEBI is proposing big changes to how it settles cases with investors and market participants. A fast-track route for disputes up to ₹10 lakh and removal of an extra 20% charge could make resolving market violations quicker and cheaper for ordinary investors.

📰 What Happened

SEBI has proposed a major overhaul of its settlement framework, including a dedicated fast-track mechanism for cases involving amounts up to ₹10 lakh.

The regulator wants to remove the additional 20% settlement charge currently levied in certain cases where multiple proceedings run simultaneously against the same party.

These proposals are open for public consultation and aim to reduce case backlogs, make the settlement process more transparent, and lower the financial burden on smaller market participants.

🎯 What You Should Do

Check if you have any pending SEBI notices or show-cause orders — the new fast-track route may apply to your case once rules are finalised.

💡

Avoid ignoring SEBI communications; settling early under the proposed framework could save you the 20% additional charge that currently applies to multiple proceedings.

Consult a SEBI-registered legal or compliance professional if you've received a notice for a trading irregularity — settlement is often faster and cheaper than full adjudication.

💡 Pro Tip

Settling a SEBI case is NOT an admission of guilt — it closes the matter without a conviction, protecting your ability to trade and invest freely in the future.

AI finds your cheapest loan from 100+ lenders

Check Your Investment Health
FCNR(B) Swap Ends: Is Your NRI Deposit Locked In?
🏦 Savings & Deposits⚠️BORROWER ALERT
40d ago
🎯
August 31 deadline

Your FCNR(B) deposit window closes a month earlier than expected

FCNR(B) Swap Ends: Is Your NRI Deposit Locked In?

🤯 An NRI parking $10,000 in FCNR(B) earns more than most Indian FDs — without currency...

Read Full Story
📋 TL;DR

RBI is closing its concessional swap facility for FCNR(B) deposits one month early — by August 31. NRIs who want better rates on USD or GBP deposits in India need to act before the window shuts.

📰 What Happened

RBI has decided to wind down its concessional swap facility for FCNR(B) deposits, with the revised deadline now set at August 31 instead of September 30.

The facility, which reduced the cost for banks to hedge foreign currency deposits, had successfully attracted strong NRI inflows into the FCNR(B) scheme.

Only deposits with a maturity of 3 to 5 years mobilised on or before August 31 will be eligible for the concessional swap rate going forward.

🎯 What You Should Do

Check with your NRI family member's bank immediately — confirm whether their planned FCNR(B) deposit can be processed before August 31 to lock in current rates.

💡

Compare current FCNR(B) interest rates across SBI, HDFC Bank, and ICICI Bank right now — rates differ by up to 0.5% and the best window closes soon.

Avoid waiting until late August — bank processing and documentation for NRI accounts often takes 7-10 business days, so initiate the deposit this week.

💡 Pro Tip

FCNR(B) interest is completely tax-free in India for NRIs during their non-resident status — no TDS deducted, making the effective yield significantly higher than a comparable resident FD.

FD vs loan EMI — which earns you more? AI will tell

Compare Now
Ayushman Bharat in Bengal: Is Your ₹5L Cover Active?
🛡️ Insurance
40d ago
💰
₹5 lakh free

Your family could get this much health cover at zero premium under Ayushman Bharat

Ayushman Bharat in Bengal: Is Your ₹5L Cover Active?

🤯 ₹5 lakh health cover costs ₹15,000–₹20,000/year privately — that's 300 cups of chai...

Read Full Story
📋 TL;DR

West Bengal is joining Ayushman Bharat from August 16, giving eligible families up to ₹5 lakh free health insurance per year. Combined with the state's own Mukhyamantri Swasthya Bima Yojana, millions of Bengalis now get cashless hospital treatment without paying a single rupee in premium.

📰 What Happened

West Bengal will implement Ayushman Bharat (PM-JAY) alongside its own Mukhyamantri Swasthya Bima Yojana from August 16, giving eligible families up to ₹5 lakh cashless health cover annually.

West Bengal was one of the last major states to stay out of the PM-JAY scheme; joining now brings millions of low- and middle-income families into India's largest government health insurance net.

Both schemes together mean beneficiaries can access cashless treatment at thousands of empanelled hospitals — government and private — without upfront payment or premium contribution.

🎯 What You Should Do

Check eligibility right now at pmjay.gov.in using your Aadhaar or mobile number — it takes under 2 minutes and costs nothing.

💡

Visit your nearest Common Service Centre or government hospital help desk after August 16 to get your Ayushman Bharat (ABHA) card printed and activated.

If you already have a basic mediclaim policy and now qualify for Ayushman Bharat, compare coverage — consider switching to a super top-up plan (covers beyond ₹5 lakh) instead of paying for a duplicate base policy.

💡 Pro Tip

Your Ayushman Bharat card works across all empanelled hospitals in every state — not just Bengal. Keep it with your Aadhaar when you travel.

Insurance + loans sorted — one app for your money

Get GoCredit
💰

Compare EMI Across 100+ Lenders

Same loan, different EMI. Find which lender saves you the most

Compare Now
99x Subscribed IPO: What Are Your Allotment Odds?
📊 Investing
40d ago
🎯
99.38x subscribed

Your IPO allotment odds just got brutally clear

99x Subscribed IPO: What Are Your Allotment Odds?

🤯 At 99x subscription, your ₹15,000 IPO bid competes with ₹14.85 lakh in rival applications.

Read Full Story
📋 TL;DR

When an IPO gets subscribed 99 times over, most retail investors go home empty-handed. Here is how allotment actually works and what you can do to improve your odds next time.

📰 What Happened

A major Indian e-commerce logistics IPO was subscribed nearly 99 times over on its final day, reflecting intense investor demand across all categories.

At such extreme oversubscription, retail investors (applying up to ₹2 lakh) face a computerised lottery for allotment, with odds below 1 in 99 per application.

Funds blocked via ASBA in oversubscribed IPOs are refunded within 6 working days if no allotment is made, per SEBI's current timeline rules.

🎯 What You Should Do

Apply through every eligible family member's separate demat account — each application is an independent lottery entry and legally multiplies your chances.

💡

Always use the ASBA (Application Supported by Blocked Amount) route through your bank's net banking or UPI ID to avoid technical rejections that disqualify your application.

Check allotment status on the registrar's website within 6 days of IPO closing — if unallotted, confirm your refund has hit your bank before investing that money elsewhere.

💡 Pro Tip

Pro tip: UPI-based IPO applications have a slightly higher technical rejection rate than ASBA via net banking — use your bank's internet portal for cleaner processing in high-demand IPOs.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
Retirement Blind Spot: Is Your ₹50L Corpus Safe?
📋 Financial Planning
41d ago
💰
₹0 planned

Most Indians never plan for cognitive decline eating their retirement savings

Retirement Blind Spot: Is Your ₹50L Corpus Safe?

🤯 A dementia patient's family spends ₹15,000–₹40,000/month on care — more than most...

Read Full Story
📋 TL;DR

Most Indians plan for inflation and long life in retirement. Almost nobody plans for the day they can no longer manage their own money — and that gap can wipe out decades of savings faster than any market crash.

📰 What Happened

Most Indian retirement plans focus on corpus size, inflation adjustment, and market risk — but skip the human risk of cognitive decline in late retirement years.

As people live longer, the period between age 75–90 increasingly involves reduced financial decision-making ability, making unmanaged investments and bank accounts a serious vulnerability.

Financial exploitation of elderly Indians — by strangers, agents, or even family — is rising, and an unplanned corpus with no governance structure is an open target.

🎯 What You Should Do

Set up a joint bank account mandate or 'either or survivor' operation with a trusted family member before you turn 60 — do not wait for a health event to force the decision.

💡

Write a one-page Investment Policy Statement listing all your accounts, FDs, mutual funds, insurance policies, and nominees — store it physically and share it with at least two trusted people.

Switch lump-sum investments to SWP (Systematic Withdrawal Plan) mode in retirement so monthly income is automated — reducing the need to actively manage or liquidate assets every month.

💡 Pro Tip

A registered Power of Attorney for financial matters costs under ₹2,000 to execute — set one up while you're healthy, not after a diagnosis makes it legally complicated.

AI finds your cheapest loan from 100+ lenders

Plan Your Retirement Now
Loan Default? 5 Legal Steps Banks Can Take
🏦 Bank Updates
41d ago
180 days

After this, your bank can legally auction your home or car without a court order

Loan Default? 5 Legal Steps Banks Can Take

🤯 A recovery agent harassing you past 7 PM is breaking RBI rules — like a shopkeeper...

Read Full Story
📋 TL;DR

If you miss loan EMIs, banks follow a step-by-step legal process before taking action. Know your rights as a borrower — from the first reminder call to asset repossession — so you can protect yourself and negotiate smartly.

📰 What Happened

Missing a single EMI triggers reminder calls and a written notice — not immediate legal action — under RBI's Fair Practices Code for lenders.

For secured loans, banks can invoke the SARFAESI Act after 90 days of default, serving a 60-day notice before repossessing or auctioning the asset.

Unsecured loan defaulters face credit bureau reporting and civil recovery suits — but no asset seizure, since no collateral was pledged.

🎯 What You Should Do

Call your lender the moment you anticipate a missed EMI and request a formal loan restructuring or moratorium in writing — this protects your record.

💡

File a written complaint with the RBI Ombudsman at cms.rbi.org.in if any recovery agent calls outside 8 AM–7 PM, uses threats, or contacts your employer without consent.

Check your CIBIL score immediately after any missed payment at cibil.com — dispute any incorrect NPA tagging within 30 days to prevent long-term credit damage.

💡 Pro Tip

Requesting a loan restructuring in writing before the 90-day default mark legally pauses SARFAESI proceedings — most borrowers never use this window.

Is your bank safe? Check lender ratings on GoCredit

Check Lenders
InvITs & Infra Bonds: Is Your ₹10,000 Working?
📊 Investing
41d ago
💰
₹3-4 billion

India's infrastructure push is now eyeing your long-term savings

InvITs & Infra Bonds: Is Your ₹10,000 Working?

🤯 The interest on a ₹1 lakh infra bond can buy you 400 cups of chai annually — most...

Read Full Story
📋 TL;DR

India's infrastructure financiers are raising billions abroad but also want domestic savings to fund roads, ports, and power projects. Here's how regular investors can participate — and earn steady returns doing it.

📰 What Happened

India's infrastructure financing institutions are planning to raise billions in foreign borrowings while also pushing for domestic long-term savings to fund large infrastructure projects.

Currently, most Indian household savings sit in FDs, PPF, and savings accounts — very little flows into infrastructure-linked investment products despite higher potential returns.

Instruments like listed InvITs and infrastructure bonds exist on Indian exchanges, allowing retail investors to earn regular income from toll roads, pipelines, and power assets.

🎯 What You Should Do

Open your broker app and search for listed InvITs (like India Grid Trust or PowerGrid InvIT) — check the latest distribution yield and compare it against your current FD rate.

💡

Check whether you hold any long-duration debt mutual funds, since falling long-term rates (driven by institutional borrowing overseas) can push up bond fund NAVs and boost your returns.

Before your next FD renewal, calculate your post-tax FD return using your actual income tax slab — if you're in 30%, you may be earning just 5% net, making infra instruments worth a serious look.

💡 Pro Tip

InvIT distributions are NOT fully taxable as income — a portion is treated as return of capital and reduces your cost of acquisition, cutting your tax outgo significantly compared to FD interest.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
Plastic ₹10 & ₹20 Notes: What Changes for You?
🏦 Bank Updates
41d ago
💰
₹10 & ₹20

Your smallest notes are getting a plastic makeover — here's what changes

Plastic ₹10 & ₹20 Notes: What Changes for You?

🤯 Plastic notes last 4x longer than paper — that's like your ₹10 surviving 400 chai...

Read Full Story
📋 TL;DR

India is set to introduce plastic polymer banknotes in ₹10 and ₹20 denominations. The government has approved RBI's proposal. These notes last longer, are harder to fake, and won't tear easily — but your wallet and daily spending stay the same.

📰 What Happened

The Indian government has formally approved RBI's proposal to introduce polymer-based plastic banknotes in ₹10 and ₹20 denominations, as confirmed in Parliament.

Polymer notes are made from a biaxially oriented polypropylene film — they are waterproof, harder to counterfeit, and typically last 4 times longer than paper currency.

No launch date has been officially announced yet; the government indicated the rollout timeline is still being determined by RBI in coordination with currency presses.

🎯 What You Should Do

Stay alert when receiving ₹10 and ₹20 notes once launched — learn the new security features (transparent window, colour-shift) so you don't mistake genuine polymer notes for fakes.

💡

Keep using old paper ₹10 and ₹20 notes normally — both will be legal tender simultaneously, so there is no need to rush to exchange or deposit them at a bank.

Avoid forwarding unverified WhatsApp messages about polymer note launch dates or new designs — wait for official RBI or government announcements to confirm details.

💡 Pro Tip

Countries like Australia and UK have used polymer notes for decades — if you spot a ₹10 that feels stiff and slightly glossy, run your thumb across it; a genuine polymer note has a distinct crisp feel unlike paper.

Is your bank safe? Check lender ratings on GoCredit

Check Lenders
📊

Free CIBIL Score Check

Check your credit score instantly — zero impact on CIBIL

Check Score Free
Arbitrage Funds: Is Your ₹10K Safer Than an FD?
📊 Investing
41d ago
📉
65-70% debt

Arbitrage funds hold this much in debt — taxed like equity, safer than stock funds

Arbitrage Funds: Is Your ₹10K Safer Than an FD?

🤯 An arbitrage fund can earn slightly more than your savings account — with near-zero...

Read Full Story
📋 TL;DR

Zerodha Fund House has launched an arbitrage mutual fund. These funds earn low but stable returns by exploiting tiny price gaps between stock and futures markets — and get taxed like equity funds, making them smarter than FDs for short-term parking.

📰 What Happened

Zerodha Fund House launched the Zerodha Arbitrage Fund, an open-ended scheme that simultaneously buys stocks in the cash market and sells equivalent futures contracts to lock in small, near-risk-free price differences.

The fund is classified as an equity mutual fund by SEBI rules since it maintains at least 65% exposure in equity and equity-related instruments, making gains eligible for equity taxation.

Arbitrage funds are considered low-risk because each stock position is hedged with a matching futures contract — the fund profits from the spread, not from market movement direction.

🎯 What You Should Do

Compare post-tax returns: calculate your FD return after subtracting your income tax slab rate, then check if a 6–7% arbitrage fund return taxed at 12.5% LTCG leaves more in your pocket.

💡

Check your investment horizon — arbitrage funds work best for money you can park for at least 3–12 months; for less than 3 months, a liquid fund may still suit you better.

Verify the fund's exit load before investing — most arbitrage funds charge a small exit load (typically 0.25%) if you redeem within 30 days, so plan your withdrawal timing in advance.

💡 Pro Tip

If you've already used up your ₹1.5 lakh 80C limit, arbitrage funds are one of the most tax-efficient places to park surplus cash in the 20–30% tax slab — no fixed maturity, no TDS deduction at source.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
NPS at ₹99: Can Gig Workers Retire Worry-Free?
📋 Financial Planning
41d ago
💰
₹99/month

You can now start your retirement fund for less than a cup of chai

NPS at ₹99: Can Gig Workers Retire Worry-Free?

🤯 ₹99 is less than a single plate of biryani — yet it can kickstart your retirement...

Read Full Story
📋 TL;DR

PFRDA now lets gig workers — Swiggy delivery partners, Ola drivers, freelancers — join the National Pension System with contributions starting at just ₹99. No minimum monthly commitment, no employer required. Your aggregator can chip in too.

📰 What Happened

PFRDA has opened the National Pension System to platform and gig workers under a flexible model called NPS e-shramik, with contributions starting at just ₹99.

Contributions can be made by the worker, the aggregator platform (like Zomato or Ola), or both — removing the traditional employer-employee structure requirement.

There is no fixed monthly minimum commitment, meaning workers can contribute based on their income flow rather than a rigid SIP-style schedule.

🎯 What You Should Do

Open an NPS account online at enps.nsdl.com or through your bank — you only need your Aadhaar, PAN, and a bank account to start.

💡

Check with your aggregator platform (Swiggy, Zomato, Ola, Urban Company) whether they are enrolling workers under the NPS e-shramik scheme and if they will co-contribute.

Compare Tier I vs Tier II NPS accounts — Tier I locks in your money until retirement with tax benefits under Section 80CCD, while Tier II gives you flexibility to withdraw anytime.

💡 Pro Tip

NPS contributions under Section 80CCD(1B) give you an extra ₹50,000 tax deduction over and above the standard ₹1.5 lakh Section 80C limit — even gig workers filing ITR can claim this.

AI finds your cheapest loan from 100+ lenders

Start Saving for Retirement
NRI Estate: 8 Steps to Stop Your Family's ₹0 Inheritance
📋 Financial Planning
41d ago
💰
₹0 received

What your family gets if you die without a will as an NRI

NRI Estate: 8 Steps to Stop Your Family's ₹0 Inheritance

🤯 A single missing nomination form can freeze ₹50L in NRI bank accounts for years —...

Read Full Story
📋 TL;DR

NRIs who skip estate planning risk leaving their families with frozen accounts, legal battles across two countries, and zero access to hard-earned savings. These 8 steps can prevent that nightmare.

📰 What Happened

NRIs with Indian property, bank accounts, and investments face complex inheritance rules spanning two legal systems — gaps in planning can freeze assets for years.

Indian succession law (Hindu Succession Act, Indian Succession Act) applies to immovable property in India regardless of where the NRI resides or which country's law their will follows.

Without valid nominations and a registered Indian will, families must pursue succession certificates through Indian courts — a process that routinely takes 1–3 years and significant legal fees.

🎯 What You Should Do

Check that every NRI bank account, FD, PPF, and demat account has an updated nominee — a missing nomination is the single most common cause of asset freezes after death.

💡

Consult an Indian lawyer to draft a separate India-specific will covering all immovable and movable assets in India, even if a foreign will already exists.

Verify FEMA repatriation rules with an RBI-authorised bank so legal heirs know the exact documentation needed to transfer inherited funds abroad without delays.

💡 Pro Tip

A registered will (registered at the Sub-Registrar's office) is far harder to contest in court than a notarised will — the registration fee is under ₹1,000 but saves lakhs in disputes.

AI finds your cheapest loan from 100+ lenders

Plan Your Finances Now
Retired but Taxed: 7 Incomes Hit Your Return
💰 Tax & Budget
41d ago
💰
₹3 lakh

Your basic tax-free limit as a senior citizen — but many retirees still owe tax

Retired but Taxed: 7 Incomes Hit Your Return

🤯 A monthly pension of ₹25,000 alone can push a senior citizen into the taxable bracket...

Read Full Story
📋 TL;DR

Retirement doesn't mean zero tax. Pension, FD interest, rent, and capital gains can all attract income tax even after you stop working. Here's what gets taxed, what's exempt, and how to plan smartly.

📰 What Happened

India's income tax rules tax several retirement income streams — pension, FD interest, rental income, and capital gains — regardless of employment status.

Senior citizens (60–80 years) get a ₹3 lakh basic exemption under both regimes; super seniors (80+) get ₹5 lakh only under the old regime.

Many retirees unknowingly skip ITR filing assuming retirement means zero tax liability, risking notices and penalties from the income tax department.

🎯 What You Should Do

Add up all income sources — pension, FD interest, rental income, dividends, capital gains — to check if your total crosses the basic exemption limit before assuming you owe nothing.

💡

Compare old vs new tax regime: if you have FD interest above ₹50,000, Section 80TTB under the old regime could save you more tax than the simplified new regime.

File your ITR even if tax payable is zero — senior citizens with income above ₹3 lakh are legally required to file, and non-filing invites Section 142(1) notices.

💡 Pro Tip

Senior citizens earning only interest income (no business income) can submit Form 15H to their bank to stop TDS deduction at source — but only if their estimated total tax liability for the year is nil.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
Judges vs Tax Dept: Does Your ITR Face Delays?
💰 Tax & Budget
41d ago
💰
₹0 tax on allowances

Judges claim certain allowances should stay tax-free under their constitutional protections

Judges vs Tax Dept: Does Your ITR Face Delays?

🤯 A Supreme Court judge's monthly salary is ₹2.8 lakh — but their allowances battle...

Read Full Story
📋 TL;DR

The Delhi High Court has told the income tax department to pause processing ITRs of High Court and Supreme Court judges. The dispute is about whether certain judicial allowances are taxable under the new tax regime. Here's what it means for regular taxpayers.

📰 What Happened

Delhi High Court directed the income tax department to halt processing of ITRs filed by Supreme Court and High Court judges under the new default tax regime.

The dispute is about whether judicial allowances — such as house rent and sumptuary allowances — can be brought under the new tax regime's tax net, given constitutional protections for judges.

Judges argue that taxing these allowances under the new regime effectively reduces their compensation after appointment, potentially violating Articles 125 and 221 of the Indian Constitution.

🎯 What You Should Do

Check your own ITR status on the income tax e-filing portal (incometax.gov.in) — this court order does NOT affect processing of regular taxpayer returns.

💡

If you are a government employee with service-specific allowances, track this case's outcome — a ruling in judges' favour could open doors for broader allowance exemption claims.

Compare old vs new tax regime benefits for your salary slab using the income tax department's free online calculator before the July 31 ITR deadline to avoid last-minute regime confusion.

💡 Pro Tip

Pro tip: Even if you filed your ITR under the new regime, you can switch back to the old regime next year if you have no business income — salaried employees get this flexibility every financial year.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
🎯

AI Loan Agent — 100+ Lenders

AI scans all lenders and finds your cheapest EMI automatically

Find Cheapest Loan
₹54L Cash Deposit, Zero ITR: How He Still Won?
💰 Tax & Budget
41d ago
💰
₹54 lakh cash deposit

Your unexplained cash deposits can trigger a tax notice within months

₹54L Cash Deposit, Zero ITR: How He Still Won?

🤯 ₹54 lakh = roughly 18 years of average Delhi auto-driver earnings — yet paperwork...

Read Full Story
📋 TL;DR

A property dealer deposited ₹54 lakh in cash, filed no income tax return, got a tax notice — and still won at the tax tribunal. Here's the legal logic behind it, and what every cash-heavy Indian must know to stay safe.

📰 What Happened

A Delhi property dealer deposited ₹54 lakh in cash received from property buyers as advance payments, but filed no income tax return for the relevant year.

The Income Tax Department issued a notice treating the deposits as unexplained cash credit under Section 68 of the Income Tax Act and sought to add the full amount to taxable income.

ITAT Delhi ruled in the dealer's favour because he successfully demonstrated the deposits were client advances — identifiable, traceable transactions — not undisclosed personal income.

🎯 What You Should Do

Maintain a client-wise cash receipt ledger with names, amounts, dates, and purpose — this single document is your primary defence if the tax department questions large deposits.

💡

File your ITR every year even if your net income is below the taxable limit — non-filing invites scrutiny and makes it harder to explain legitimate high-value bank credits later.

If you receive cash on behalf of clients as an agent or broker, document each transaction with a written agreement or acknowledgement receipt before depositing the money in your account.

💡 Pro Tip

Under Section 68, the burden of proof shifts to YOU to explain cash credits in your bank account — but if you prove the source, nature, and genuineness of deposits with documents, the addition cannot legally stand, regardless of your ITR filing status.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
RBI Bars Loan Agents: 7 Rights You Now Have
🏛️ RBI Policy
41d ago
🎯
10 PM hard stop

Your loan agent cannot call or visit you after this hour — ever

RBI Bars Loan Agents: 7 Rights You Now Have

🤯 More protected from your lender than from spam calls — that's India in 2025.

Read Full Story
📋 TL;DR

RBI has released strict rules on how banks and NBFCs can recover loans. Lenders and their agents cannot threaten, harass, or make surprise visits. Borrowers now have clear rights — and a path to complain if those rights are broken.

📰 What Happened

RBI has issued a formal framework capping loan recovery calls between 8 AM and 7 PM, banning contact outside these hours on any day.

Lenders and their hired recovery agents are now explicitly barred from using threats, abusive language, or contacting the borrower's family, employer, or neighbours.

Borrowers must receive advance notice before any field visit, and agents are required to carry a written authorisation letter from the lending institution at all times.

🎯 What You Should Do

Note the time and date of every recovery call or visit you receive — this log is your evidence if an agent violates the 8 AM–7 PM rule.

💡

Ask any recovery agent to show their authorisation letter from the lender before speaking to them; if they refuse, end the interaction and report it.

File a complaint at cms.rbi.org.in (RBI Ombudsman portal) if your lender does not resolve a recovery harassment grievance within 30 days — it is free and formal.

💡 Pro Tip

Pro tip: If a recovery agent contacts your employer or a family member who is not a co-borrower, that alone is grounds for an RBI Ombudsman complaint — lenders can face penalties for this specific act.

RBI rules change your EMI — check your current rate

Compare Rates
New AMC hits ₹600 Cr AUM: Is Your Fund Choice Wider?
📊 Investing
41d ago
💰
₹600 crore

A new AMC crossed this AUM in just 12 months — here's what it means for your SIP choices

New AMC hits ₹600 Cr AUM: Is Your Fund Choice Wider?

🤯 ₹600 crore AUM sounds huge — but India's top AMC manages over ₹10 lakh crore. That's...

Read Full Story
📋 TL;DR

A new mutual fund house hit ₹600 crore in assets within its first year, backed by 13,000 investors. More AMCs entering the market means more fund choices for Indian investors — but picking the right one still needs careful thought.

📰 What Happened

A relatively new mutual fund house completed its first year of operations, crossing ₹600 crore in assets under management across four fund schemes.

The AMC attracted approximately 13,000 investors in its first year, signalling growing investor appetite for newer, research-driven fund houses in India.

The fund house is planning to expand its product lineup into mid-cap and small-cap fund categories, which are among the highest-demand segments for Indian retail SIP investors.

🎯 What You Should Do

Check the fund fact sheet of any new AMC before investing — look at portfolio concentration, expense ratio, and the fund manager's track record at previous AMCs, not just the new house.

💡

Compare the Total Expense Ratio (TER) of a new AMC's funds against established peers on SEBI's MF data portal (mfcentral.in) — lower TER directly boosts your long-term returns.

Avoid making a new or small AMC's fund your primary SIP holding until it has at least one full market cycle (3-5 years) of audited NAV history across a bull and bear phase.

💡 Pro Tip

When a new AMC launches, its NFO (New Fund Offer) price of ₹10 feels cheap — but ₹10 NAV means nothing. A fund's value comes from its portfolio quality, not its face value.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
EPS Pension at ₹1,000: Are You Losing ₹6,500/Month?
📋 Financial Planning
41d ago
💰
₹6,500/month

The gap between what EPS pensioners get now and what they deserve

EPS Pension at ₹1,000: Are You Losing ₹6,500/Month?

🤯 ₹1,000/month pension won't even cover a monthly metro card in Delhi — chai included.

Read Full Story
📋 TL;DR

Millions of retired EPFO members still get just ₹1,000 a month as minimum pension under EPS-95. A long-pending demand to raise it to ₹7,500 has not been approved yet. Here is what you need to know and what it means for your retirement plan.

📰 What Happened

The EPS-95 minimum pension has remained frozen at ₹1,000 per month since 2014, despite inflation eroding its real value significantly over the past decade.

Pensioner organisations and unions have demanded the minimum be raised to ₹7,500 per month, but no official gazette notification from the Labour Ministry or EPFO has been issued as of mid-2025.

The EPS pension formula is based on years of pensionable service and average salary capped at ₹15,000/month, meaning most low-wage workers receive amounts far below even the current ₹1,000 floor without a government top-up.

🎯 What You Should Do

Log into your EPFO UAN portal at unifiedportal-mem.epfindia.gov.in and verify your full service history — any gap in contributions directly reduces your eventual EPS pension amount.

💡

Calculate your projected EPS pension using the formula: (Pensionable Salary × Pensionable Service) ÷ 70 — if the number is below ₹5,000/month, start a separate NPS or SIP immediately to fill that gap.

Avoid retiring early without checking your EPS eligibility — you need a minimum 10 years of pensionable service to qualify for any monthly pension; below that, you only get a withdrawal benefit.

💡 Pro Tip

If you have over 20 years of EPS service, you get a 2-year bonus added to your pensionable service — this can meaningfully bump your monthly pension without any extra contribution from you.

AI finds your cheapest loan from 100+ lenders

Plan Your Retirement Now
Filed ITR on Time? 3 Moves That Trigger Notices
💰 Tax & Budget
41d ago
🎯
3 hidden triggers

Your on-time ITR can still get you a tax notice

Filed ITR on Time? 3 Moves That Trigger Notices

🤯 A ₹500 FD interest you forgot to declare can snowball into a ₹5,000 penalty notice.

Read Full Story
📋 TL;DR

Filing your ITR before July 31 doesn't mean you're safe. Mismatches in your AIS data, wrong deduction claims, and small errors in the return itself can still invite a tax notice — even months later.

📰 What Happened

The Income Tax Department's automated system matches your ITR data against AIS, Form 26AS, and third-party reports from banks, brokers, and registrars — any gap triggers a notice.

Common triggers include undeclared interest income, inflated 80C or HRA claims, and high-value transactions like large cash deposits or property deals that don't match reported income.

Notices can arrive months after filing — under Section 143(1)(a) for mismatches, Section 139(9) for defective returns, or Section 148 for suspected income escaping assessment.

🎯 What You Should Do

Download your AIS and Form 26AS from the income tax portal (incometax.gov.in) today and compare every figure — interest, dividends, TDS — against what you declared in your ITR.

💡

Check all deduction claims you made under 80C, 80D, and HRA — ensure you have physical or digital proof (premium receipts, rent agreements, investment certificates) ready in case of scrutiny.

If you spot a mismatch or error in your already-filed ITR, file a revised return before December 31 of the assessment year — this is far less costly than responding to a formal notice.

💡 Pro Tip

If you receive a 143(1)(a) mismatch notice, you can respond online within 30 days through the e-proceedings tab — no CA visit needed for simple mismatches.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
🛡️

Recovery Harassment? Get Help

Loan Kavach: legal team fights harassment calls for you

Get Protection
SIF AUM Up 30%: Should You Invest ₹10L Here?
📊 Investing
41d ago
💰
₹23,177 crore

Your new investment option is quietly becoming a serious category

SIF AUM Up 30%: Should You Invest ₹10L Here?

🤯 ₹23,177 crore is roughly what 77 lakh Indians spend on chai every single month — and...

Read Full Story
📋 TL;DR

Specialised Investment Funds — a new SEBI-regulated category between mutual funds and PMS — have crossed ₹23,177 crore in assets. They need a ₹10 lakh minimum investment. Here's what that means for you.

📰 What Happened

Specialised Investment Funds — a SEBI-regulated category launched in 2024 — crossed ₹23,177 crore in AUM in July 2026, up roughly 30% in a short period.

SIFs require a minimum investment of ₹10 lakh per strategy and can use more flexible mandates than standard mutual funds, including derivatives and concentrated bets.

The number of folios (investor accounts) in SIFs is approaching 1 lakh, suggesting growing but still niche adoption among HNI and upper-retail investors.

🎯 What You Should Do

Check your investable surplus first — only consider SIFs if you already have a solid emergency fund, term insurance, and at least ₹15–20 lakh in diversified mutual funds.

💡

Compare the full fee structure (management fees, performance fees, exit loads) of any SIF your advisor recommends before committing your ₹10 lakh minimum.

Verify that any SIF you invest in is listed on the SEBI-registered intermediary database — do not invest based solely on a distributor's verbal pitch or brochure.

💡 Pro Tip

SIF returns are NOT directly comparable to mutual fund returns — their benchmarks and strategy types differ. Always ask for a risk-adjusted return figure, not just absolute returns.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
Gold Drops ₹8,000: Buy the Dip or Wait More?
📊 Investing
41d ago
💰
₹8,000+ drop

Gold has fallen this much in days — your SGB or jewellery just got cheaper

Gold Drops ₹8,000: Buy the Dip or Wait More?

🤯 ₹8,000 drop in gold = roughly 3 months of a Mumbai family's grocery bill

Read Full Story
📋 TL;DR

Gold prices have fallen sharply on Indian commodity exchanges. For buyers, this could be a good entry point. But before you rush to buy jewellery or sovereign gold bonds, here's what you actually need to know.

📰 What Happened

Gold prices on MCX fell sharply, dipping below ₹1.54 lakh per 10 grams amid profit-booking after a sustained rally.

Silver prices dropped by over ₹3,200 per kilogram on MCX in the same session, reflecting broader commodity market weakness.

A partial recovery in the US dollar index added pressure on precious metals, as a stronger dollar makes gold costlier for global buyers and reduces demand.

🎯 What You Should Do

Compare Gold ETF prices today on your mutual fund app — they track live MCX rates and let you buy even ₹500 worth without making charges.

💡

If you planned to buy gold jewellery for a wedding or occasion in the next 3 months, consider purchasing now rather than waiting for a further dip that may not come.

Avoid selling your existing SGBs or Gold ETFs in panic — short-term dips in gold are common and the long-term return story remains intact for portfolio hedging.

💡 Pro Tip

Gold ETFs bought during price dips carry zero GST and no making charges — you capture the full price upside when rates recover, unlike physical jewellery.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
NRO vs NRE: 30% Tax Gap Draining Your Interest?
💰 Tax & Budget
41d ago
📉
30% TDS on NRO interest

Your NRO account silently loses 30% to tax — do you know which account you hold?

NRO vs NRE: 30% Tax Gap Draining Your Interest?

🤯 NRE FD at 7.5% tax-free = ₹7,500/₹1L kept. Same ₹1L in taxable NRO FD at 8.5% nets...

Read Full Story
📋 TL;DR

NRIs earn interest on three account types — NRE, FCNR, and NRO. NRE and FCNR interest is fully tax-free in India. NRO interest is taxable at 30% TDS. Knowing the difference can save lakhs annually.

📰 What Happened

NRE and FCNR account interest is fully exempt from Indian income tax under Section 10(4) of the Income Tax Act, as long as the account holder maintains valid NRI status under FEMA.

NRO account interest is taxed at a flat 30% plus applicable surcharge and cess — banks deduct TDS at this rate before crediting interest to the account holder.

NRIs from countries with a Double Tax Avoidance Agreement (DTAA) with India — such as the US, UK, UAE, and Canada — may claim a lower TDS rate on NRO interest by submitting a Tax Residency Certificate to their bank.

🎯 What You Should Do

Call your bank today and confirm whether your accounts are classified as NRE, NRO, or FCNR — do not assume based on the account name alone.

💡

If you hold an NRO account and your country of residence has a DTAA with India, submit a Tax Residency Certificate (TRC) to your bank to reduce TDS below 30%.

If you are returning to India permanently, notify your bank immediately to redesignate your NRE/FCNR accounts — delaying this exposes you to tax liability on interest that would otherwise be exempt.

💡 Pro Tip

NRIs can claim TDS refunds on NRO interest by filing an ITR in India if total Indian income falls below the basic exemption limit — most NRIs skip this and leave money on the table.

Tax saved = EMI reduced — find your cheapest loan

Find Cheapest Loan
New to MFs? 3 Fund Types for Your 2025 Goals
📊 Investing
41d ago
💰
₹1 lakh → ₹5.4 lakh

What a 15-year flexi-cap SIP can grow your money to

New to MFs? 3 Fund Types for Your 2025 Goals

🤯 A ₹5,000/month SIP costs less than most Indians spend on dining out — yet it can build...

Read Full Story
📋 TL;DR

Confused about where to put your money in mutual funds right now? Whether you are a first-time investor or building a retirement corpus, the right fund type depends on your goal and how long you can stay invested. Here's a plain-English breakdown.

📰 What Happened

Market volatility in 2025 has prompted Indian investors to reassess mutual fund allocations, with experts highlighting flexi-cap and multi-asset funds as suitable starting points.

Small-cap and international funds are back in discussion as long-term plays, but advisors caution that these carry higher risk and need a 7-10 year commitment.

For retirement-focused investors, a staggered approach — equity SIPs in early years shifting to hybrid or debt funds closer to the goal — is widely recommended.

🎯 What You Should Do

Check your investment horizon first: if it's under 3 years, avoid pure equity funds entirely and look at short-duration debt or liquid funds instead.

💡

Start a ₹1,000-5,000 monthly SIP in a SEBI-registered flexi-cap fund if you are a first-time investor — diversification is built in and risk is managed by the fund manager.

Review your existing SIPs once a year against your goal, not against Sensex movements — exit only if your personal financial goal has changed, not because markets dipped.

💡 Pro Tip

Pro tip: In a flexi-cap fund, check the large-cap allocation percentage in the factsheet — funds holding 60%+ in large caps behave more like stable index funds, which is ideal for new investors who get nervous in downturns.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
India's Credit Boom: Who Gets Left Out?
📊 Credit Score
41d ago
💰
50 crore adults

This many Indians still lack access to formal credit — are you one of them?

India's Credit Boom: Who Gets Left Out?

🤯 India's formal credit gap is larger than the entire population of the US — yet we call...

Read Full Story
📋 TL;DR

India's loan market is growing fast, thanks to digital lending and fintech. But millions of salaried workers, farmers, and small business owners still can't get a bank loan. Here's why — and what you can do if you're credit-invisible.

📰 What Happened

India's retail credit market is growing at roughly 14–16% annually, driven by home loans, personal loans, and BNPL products through digital channels.

Despite this growth, an estimated 40–50 crore Indian adults remain credit-invisible — no formal loan record or credit score that banks can assess.

Digital lenders and fintechs are using alternative data like UPI history and GST filings to underwrite new-to-credit borrowers, but at significantly higher interest rates.

🎯 What You Should Do

Check your CIBIL score for free on the CIBIL website or through your bank app — if it says 'NH' or '-1', you are credit-invisible and need to act now.

💡

Open a secured credit card against a fixed deposit of ₹10,000–₹25,000 at your bank — use it for small monthly expenses and pay the full bill every month to build a clean credit trail.

If you run a small business, register on the GST portal and maintain UPI-based transactions — this digital footprint is now used by RBI-registered NBFCs to offer you formal loans at lower rates.

💡 Pro Tip

A 'NH' CIBIL score is not a bad score — it means 'no history'. One secured card used for 6–12 months can unlock your first unsecured loan eligibility.

Check your CIBIL score for free — instant result

Check Score
📈

Improve CIBIL by 100 Points

AI analyzes your report and gives a personalized action plan

Boost My Score
Old Paper Shares? Convert to Demat or Lose Value
📊 Investing
41d ago
💰
₹0 value

Your old paper shares may be worthless until converted to demat

Old Paper Shares? Convert to Demat or Lose Value

🤯 Some forgotten paper shares in an old almari could be worth more than 6 months of...

Read Full Story
📋 TL;DR

Millions of Indians still hold old physical share certificates that can't be traded. SEBI has made it easier to convert them to demat form. Here's what you need to know before your shares become untradeable.

📰 What Happened

SEBI has simplified the process for converting old physical share certificates into demat form, making it easier for retail investors to unlock legacy holdings.

Physical share certificates of listed companies cannot be sold or transferred on Indian stock exchanges — demat conversion is mandatory for any transaction since April 2019.

A structured framework now exists for handling difficult cases — including shares of merged, delisted, or dormant companies — through depositories and the IEPF authority.

🎯 What You Should Do

Search your home files, lockers, and family paperwork for old share certificates — especially inherited ones from parents or grandparents.

💡

Contact your SEBI-registered Depository Participant (DP) or broker with your original certificates and a filled Demat Request Form (DRF) to begin conversion.

Check that your name, address, and PAN in your demat account KYC exactly match the details printed on the physical certificate — fix mismatches before submitting.

💡 Pro Tip

Pro tip: If a company on your old certificate has been acquired or merged, the shares may have been converted into the acquirer's stock — check the BSE/NSE corporate action history before assuming the holding is worthless.

Investing is step 1. Step 0? Get your CIBIL score right

Check CIBIL Free
Women's Term Plan: Save 15% on Premiums for Life?
🛡️ Insurance
41d ago
📉
15% lifetime discount

Your term insurance premium stays lower every single year you hold the policy

Women's Term Plan: Save 15% on Premiums for Life?

🤯 A 15% lifetime discount on a ₹1 crore term plan can save a 30-year-old woman over...

Read Full Story
📋 TL;DR

ICICI Prudential has launched a term life insurance plan made exclusively for women, offering a 15% lifetime premium discount, a pregnancy break option, and critical illness cover for women-specific health conditions. Here's what you need to know before buying.

📰 What Happened

ICICI Prudential Life Insurance launched iProtect Smart Her, a term life insurance plan designed exclusively for women buyers in India.

The plan offers a 15% lifetime discount on premiums compared to standard rates, plus a pregnancy break option that lets policyholders pause payments during maternity.

The plan includes critical illness benefits covering women-specific conditions such as breast cancer, cervical cancer, and complications related to pregnancy and childbirth.

🎯 What You Should Do

Compare the discounted premium of this plan against a standard gender-neutral term plan of equal sum assured on an insurance aggregator before deciding.

💡

Check the exact terms of the pregnancy break — confirm how many months you can pause, whether the policy tenure extends, and if any interest or penalty applies.

Review the women-specific critical illness rider list carefully and ensure conditions like breast cancer, cervical cancer, and ovarian cancer are covered with clear payout rules — not buried under vague definitions.

💡 Pro Tip

Pro tip: A lifetime premium discount compounds in value the younger you buy — a 25-year-old locking in a 15% discount saves significantly more in absolute rupees over 35 years than a 35-year-old buying the same plan.

Insurance + loans sorted — one app for your money

Get GoCredit
Gig Worker? 5 Money Rules to Survive No Salary
📋 Financial Planning
41d ago
💰
₹0 salary protection

Your income can vanish overnight — no PF, no gratuity, no safety net

Gig Worker? 5 Money Rules to Survive No Salary

🤯 A ₹60K/month freelancer with no emergency fund is one bad month away from skipping...

Read Full Story
📋 TL;DR

Freelancers and gig workers earn without a fixed salary, PF, or job security. Here are five practical money rules to build financial stability when your income comes in waves — not waves of fixed monthly transfers.

📰 What Happened

Freelancers and gig workers in India have no EPF, gratuity, or fixed salary — making financial planning structurally different from salaried employees.

AI tools are automating entry-level freelance tasks like content writing, basic design, and data work, creating real income risk for undiversified gig workers.

India's gig economy is estimated to employ over 1.5 crore workers, yet most lack health cover, retirement savings, or an emergency fund of any size.

🎯 What You Should Do

Open a separate savings account and auto-transfer 30% of every freelance payment the day it arrives — treat it as non-negotiable before spending anything.

💡

Buy an individual health insurance policy of at least ₹10 lakh immediately if you don't have corporate group cover — compare plans on IRDAI-registered aggregators.

File ITR-3 or ITR-4 every year and claim all legitimate business deductions (internet, equipment, workspace) to legally reduce your taxable freelance income.

💡 Pro Tip

Deposit advance tax quarterly (June, September, December, March) if your annual freelance income exceeds ₹1 lakh — missing this triggers interest under Sections 234B and 234C on top of your tax bill.

AI finds your cheapest loan from 100+ lenders

Plan Your Money Now
Micro-LAP Loans: Is Your Property Worth the Risk?
🏦 Bank Updates
41d ago
💰
₹5–25 lakh

Your property can unlock this much — but micro-LAP traps are real

Micro-LAP Loans: Is Your Property Worth the Risk?

🤯 A ₹10L micro-LAP EMI can swallow 40% of a small shop owner's monthly income — more...

Read Full Story
📋 TL;DR

Micro Loan Against Property lets small borrowers pledge their house or shop for ₹5–25 lakh loans. Sounds useful, but high rates and long tenures mean your property is at real risk if business slows down. Know before you sign.

📰 What Happened

Major microfinance NBFCs are expanding into micro-LAP — small loans of ₹5–25 lakh secured against residential or commercial property owned by low-to-middle income borrowers.

Sector consolidation is accelerating as larger players acquire smaller micro-LAP focused NBFCs to grow their secured loan books and reduce portfolio risk from unsecured microfinance.

Micro-LAP is growing because lenders see it as safer than unsecured MFI loans, but for borrowers it means their home or shop is now on the line for business or personal credit needs.

🎯 What You Should Do

Compare micro-LAP interest rates across at least 3 NBFC and bank lenders — rates vary widely from 16% to 24%, and even 2% difference on ₹10 lakh over 10 years costs you ₹1.3 lakh extra.

💡

Check whether your lender is RBI-registered on the RBI website before pledging property — unregistered lenders cannot legally enforce SARFAESI, but can still harass borrowers.

Explore MUDRA Tarun loans (up to ₹10 lakh, no collateral required) or PM SVANidhi before committing your property — unsecured government-backed schemes are a safer first step.

💡 Pro Tip

If your micro-LAP lender gets acquired, your loan account transfers automatically — but immediately save the new lender's RBI registration number and grievance officer contact so you're not stranded if disputes arise.

Is your bank safe? Check lender ratings on GoCredit

Check Lenders
Byju's Collapse: Can You Recover Your Money?
📱 Fintech News⚠️BORROWER ALERT
41d ago
💰
₹53+ crore

Your edtech fees and deposits may be gone — here's what to know

Byju's Collapse: Can You Recover Your Money?

🤯 ₹53 crore owed to one investor alone — that's 5.3 lakh months of chai for an average...

Read Full Story
📋 TL;DR

Byju's is fighting multiple creditors in court while still owing money to students, teachers, and investors. If you paid fees or have a refund pending, here is what you can actually do to protect yourself.

📰 What Happened

Qatar Holding has filed a fresh plea in Karnataka High Court seeking over ₹53 crore from Byju Raveendran personally, stemming from an arbitration award.

Byju's, once India's most valued edtech startup, has faced multiple insolvency proceedings, creditor disputes, and regulatory scrutiny over the past two years.

Thousands of students, teachers, and small vendors are also owed money — from fee refunds to unpaid salaries — making recovery uncertain for ordinary claimants.

🎯 What You Should Do

File a formal claim with the NCLT-appointed Resolution Professional if you have any unpaid refund or dues from Byju's — this is the only legal way to be counted as a creditor.

💡

Raise a chargeback dispute with your credit card issuer or bank immediately if you paid fees that were never delivered — time limits apply, so act within 30-180 days of the failed service.

Check your education loan agreement — if the course was incomplete or cancelled, contact your lender in writing to explore whether EMIs can be paused or restructured.

💡 Pro Tip

Pro tip: Under IBC rules, you must submit your claim before the deadline set by the Resolution Professional — late claims are routinely rejected with no exceptions, even for genuine cases.

AI finds your cheapest loan from 100+ lenders

Check Your Loan Options

Sabse Sasta Loan Offer Chahiye?

AI 100+ lenders scan karke tumhare liye best offer dhundta hai — CIBIL pe zero asar.

Get Real Offers — Free →

Get 800+ CIBIL Score with AI

Free · No spam · CIBIL pe zero asar

Boost Score